Landlords check eviction history by reviewing tenant screening reports, court eviction records, and past rental filings to assess rental risk. Tenants can check the same records in advance to understand what appears on their file and avoid surprises during the application process.
Even a single dismissed filing can still influence a screening decision. This guide covers how both sides access those records, how long they stay visible, and what the law allows landlords to ask.
How Tenants Can Check Their Own Eviction History?
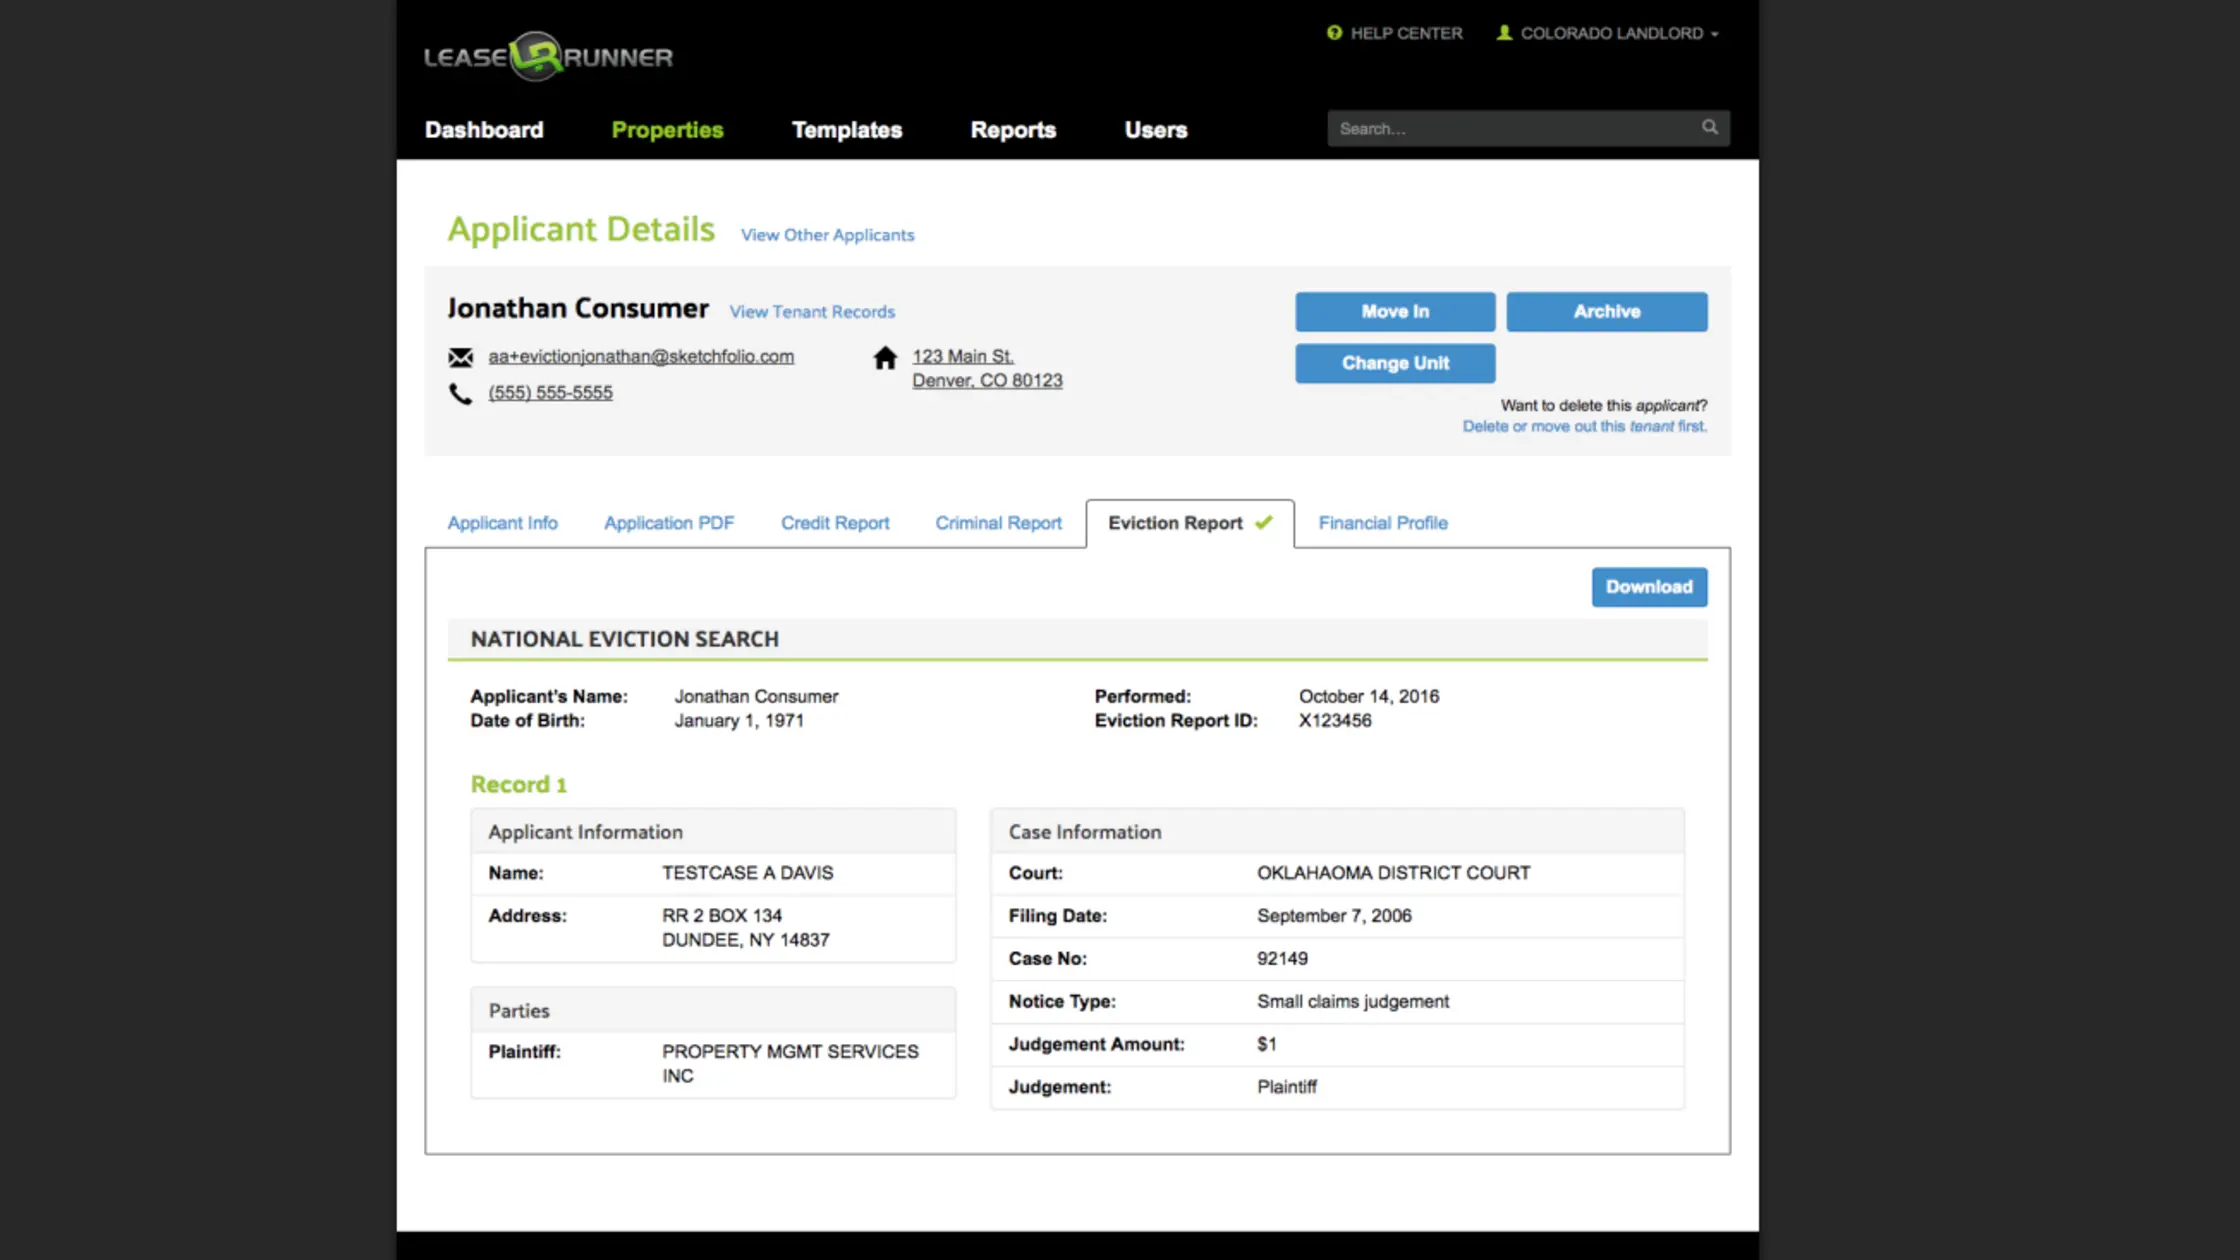
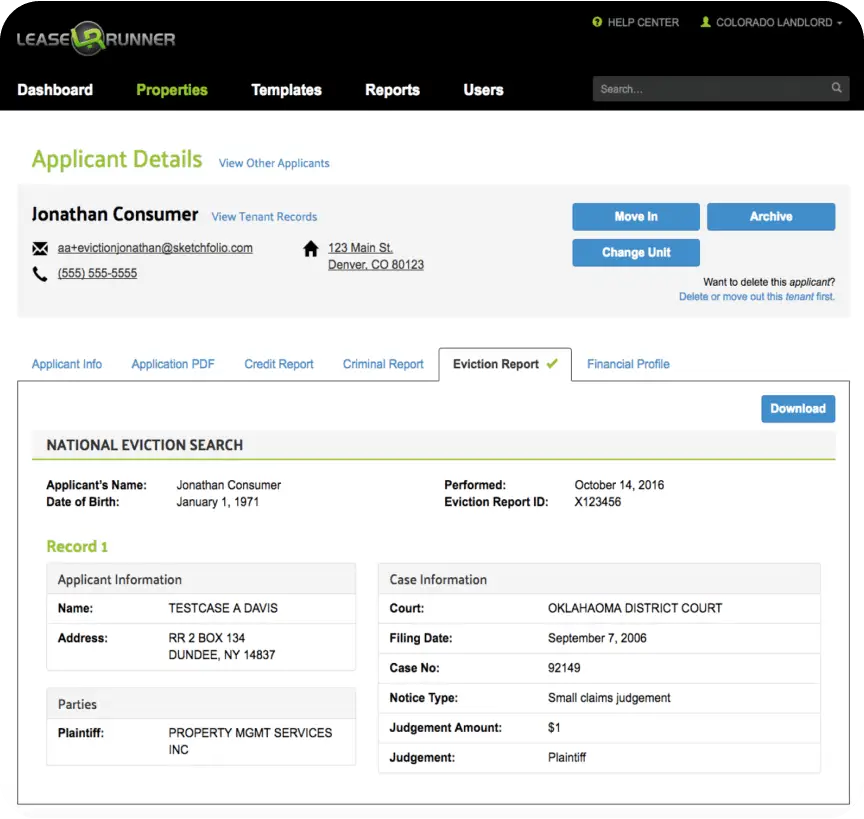
The report above shows what a LeaseRunner eviction search result looks like. Here is what each field means:
- Applicant's Name. This is the name used to run the search. If you have ever used a different name, check whether the report also searched for that version.
- Performed. This is the date the search was run, not the date of the eviction itself.
- Eviction Report ID. This is the report's unique reference number. Keep it if you need to contact LeaseRunner or dispute a result.
- Record 1 (or Record 2, etc.). Each eviction filing appears as a separate numbered record. Multiple records mean multiple filings in your history.
- Name under Applicant Information. This is the name tied to the court case. It may differ from your current legal name if you changed your name after the filing.
- Plaintiff. This is the landlord or property management company that filed the case. A property management company name here means a corporate landlord initiated the filing.
- Court. This shows which court handled the case. Compare this against your past rental addresses. If the court location does not match anywhere you have lived, the record may belong to someone else with the same name.
- Filing Date. This is when the landlord submitted the case to court. Under the FCRA, this record can appear on a screening report for up to seven years from this date.
- Case No. This is the court's ID for the filing. Write it down if you need to contact the clerk or file a dispute.
- Notice Type. This shows the case's legal category. "Small claims judgement" means the case was handled in small claims court, typically for lower dollar amounts.
- Judgement Amount. This is the dollar amount the court ordered to be paid.
- Judgement. This is the outcome. "Plaintiff" means the court ruled in the landlord's favor. "Dismissed" means the case was dropped or resolved in your favor.
Knowing your eviction history is an important step for renters preparing for future housing applications. Checking your record helps you identify errors, understand how landlords might view your rental background, and plan to address any issues. Here are practical ways tenants can check their own eviction history:
Check Court Records Online
Start here if you have ever had a lease dispute, a missed payment, or left a rental before your lease ended.
- Step 1: Search the county where your rental property was located, not where you live now. If you rented in more than one county or state, search each county or state separately.
- Step 2: Go to the civil or housing court portal for that county. Search your full legal name as it appeared on your lease. Look for cases labeled "eviction," “unlawful detainer," or “forcible entry." If you have used another name, search that too.
- Step 3: Check the outcome of each result. Note whether the case was filed, dismissed, or became a judgment. A dismissed case may still show up in public records unless a court has sealed it.
- Step 4: If a record is wrong or qualifies for sealing, write down the case number and the court's contact details. Some courts let you file a dispute online. Others need a written request or an in-person visit.
Use Tenant Screening Services
Tenant screening services pull data from court records, eviction databases, and credit files into a single rental history report. They search across multiple states at once, so they often catch records a single county search would miss.
The Fair Credit Reporting Act gives you the right to request your own consumer report. Platforms like LeaseRunner's tenant screening service let you request your own report directly. That way, you see what landlords will see before you apply. Once you have the report, check two things: whether the records are accurate, and whether any entries can be disputed.
Watch how each entry is labeled. A dismissed case may still appear without showing the outcome. If anything is wrong, dispute it with the reporting agency. They must fix verified errors within 30 days. Reviewing your report first also helps you talk to landlords with confidence.
Check Credit Reports
Eviction filings do not show up directly on credit reports. What does show up is the financial damage. A landlord who sued for unpaid rent may have left a civil judgment on your report. Unpaid rent sent to collections will appear as a collection account. Both can stay on your report for up to seven years.
You get one free report per year from each of the three major bureaus at AnnualCreditReport.com. Pull it before you apply. Look for any judgment or collection account tied to a past rental.
Credit scores have a known gap. A score reflects loan and credit card repayment, not whether you pay rent on time. Renters who have never held a credit card or loan can score low, even with a strong rent history. The score measures borrowing behavior, not tenancy behavior.
The industry is moving toward bank-verified income and rent payment history. This approach reads income deposits and spending patterns directly from a financial institution. It answers a more relevant question for landlords: Can this person afford this specific rent?
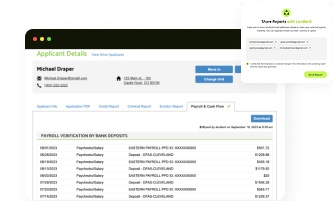
Tenants can request their own screening report to see what landlords see. LeaseRunner offers a portable tenant screening report that you generate once and share across multiple applications. It covers income, cash flow, and rental history without triggering a new credit pull each time.
Contact the Court Clerk
Go to the court clerk when an online portal is incomplete or shows no results. Clerk offices hold the full record of all civil and housing case filings, including ones not yet in public databases.
Before you call or visit, have these ready: your full legal name as it appeared on your lease, the rental property address, and the dates you lived there.
Ask for a search of civil and housing filings under your name for that county and time period. Request the case status, whether it was filed, dismissed, or became a judgment. If a judgment exists, ask whether your state allows you to file a satisfaction of judgment once the debt is paid.
Some courts charge a small fee for certified copies. A certified copy carries more weight than a portal printout when presenting records to a new landlord.
Review State-Specific Eviction Databases
Some states have eviction tracking systems and legal aid databases that go beyond what county portals show. These help you find records across multiple areas, check a case's current status, and get support disputing or sealing a record.
The Eviction Lab at Princeton University runs the Eviction Tracking System. It tracks eviction filing trends across major U.S. cities. It is a research tool rather than a personal lookup, but it shows how active filings are in your area and what state protections exist.
Legal aid organizations are your best resource for understanding tenant rights and resolving record disputes. Many offer free consultations for tenants dealing with wrong or outdated records." Find one at lawhelp.org.
If your state has an eviction sealing law, a legal aid attorney can tell you if your case qualifies and how to file. Act on this before you apply for new housing, not after a denial.
How Long Does an Eviction Stay on a Tenant’s Record?
In most cases, eviction information can remain visible for up to 7 years. If a court issues an eviction judgment against a tenant, that judgment may appear on credit reports for as long as seven years and is also captured by many tenant-screening databases during that period. By contrast, an eviction filing—the landlord’s initial case submitted to court—usually does not affect credit scores, but it can still show up in public court records and third-party screening reports for several years and may influence a landlord’s decision.
Understanding this filing versus judgment distinction explains why two renters with “evictions” on record can face very different outcomes: a dismissed filing may still surface in a background check, while a judgment is the stronger red flag. Duration isn’t uniform everywhere, either.
Some states are starting to pass laws that limit how eviction records can be used, especially in cases where the eviction was dismissed or filed during emergency periods (like during the COVID-19 pandemic). In a few places, eviction records can even be sealed after a certain period.
State-level protections vary widely. The table below covers the most populated rental markets and what each currently offers tenants.
So what does this mean for tenants? In fact, it can affect future housing opportunities, rental applications, and even financial credibility. By understanding the difference between filings and judgments, checking both public records and tenant screening reports, and being aware of state-specific protections, tenants can take proactive steps to address inaccuracies, seal eligible records, and plan for future rentals.
Can You Remove an Eviction From Your Record?
When it comes to background checks, the choice between "free" DIY methods and professional “paid" reports is often a trade-off between saving money and ensuring accuracy. While free searches are tempting, they often lack the depth required to make a secure financial decision.
Paid tenant screening services aggregate data from multiple sources into a single, structured report.
Strengths
- Multi-jurisdictional record searches
- Clear labeling of filings, dismissals, and judgments
- Integrated context from credit and rental history
- Reduced risk of name-based mismatches
- Faster, standardized, and legally compliant process
Limitations
- Requires applicant consent
- Comes with a screening fee
- Still depends on the accuracy of public source reporting
Paid reports focus on decision clarity, not just data access. They help landlords understand what the eviction record means, not just whether one exists.
How Landlords Can Check for Tenants’ Evictions?
For landlords, knowing a prospective tenant’s eviction history is a key part of risk management. A thorough check helps reduce the chance of future rental loss, property damage, or legal disputes.
Below are the four most reliable methods landlords use, broken down into clear, actionable steps.
1. Search Local Court Records
Court filings are the primary source of eviction data. Because cases are filed at the county level, your accuracy depends on having verified addresses for every jurisdiction where the applicant previously rented.
- Step 1: Collect every prior rental address from the applicant's history, not just their most recent one. Eviction cases are tied to the property's jurisdiction, not where the applicant currently lives. A case filed in Cook County, Illinois, will not appear in a Texas court database.
- Step 2: Check the addresses the applicant disclosed against the timeline on their application. Any gap longer than two months with no listed address is worth following up on. Ask the applicant to account for that period before you run your search.
- Step 3: Run the search using the applicant's full legal name in the civil or housing court portal for each county where they previously rented. Look specifically for case types labeled "eviction," “unlawful detainer," or “forcible entry."
These three terms describe the same legal action under different state naming conventions: unlawful detainer applies when a tenant remains on a property after their legal right to occupy it has ended; forcible entry applies when a tenant retains possession without authorization after a notice has been served. If the applicant has used multiple names or aliases, run a separate search for each.
- Step 4: If a county portal is incomplete or unavailable, contact the court clerk's office directly. Many counties accept in-person or written records requests. Document your search steps for each applicant so your process stays consistent and defensible across all applications.
2. Request a Tenant Screening Report
Using a professional service is the most efficient way to aggregate data from multiple states and databases simultaneously.
- Step 1: Choose a Reputable Provider: Services like TransUnion SmartMove or Experian RentBureau are industry standards. For a more streamlined experience, LeaseRunner's all-in-one screening platform offers eviction checks, credit reports, and income verification.
- Step 2: Obtain Tenant Consent: Before running any report, ensure you have written authorization from the applicant to remain compliant with the Fair Credit Reporting Act (FCRA).
- Step 3: Analyze the Results: Review the report for any "skipped" addresses or aliases that the tenant might not have disclosed.
3. Review Credit Reports
While a credit report doesn't always list an eviction directly, it reveals the financial aftermath of a broken lease.
- Step 1: Look for Monetary Judgments: If a landlord sued for unpaid rent and won, the court records a civil judgment against the former tenant. A civil judgment is a formal court ruling that one party legally owes a debt to another. That entry can appear on a credit report for up to seven years and signals to future landlords that a prior tenancy ended in legal action, not just a missed payment.
- Step 2: Check Collection Accounts: Debt from apartment complexes or property management companies sent to collections is a major red flag for past rental issues.
- Step 3: Assess Financial Stability: Look for patterns of late payments or high debt-to-income ratios that might indicate a high risk of future eviction.
4. Direct Rental Verification
A report tells you what happened, but a previous landlord can tell you why.
- Step 1: Verify the Reference: Cross-reference the contact name provided with public property records to ensure you are speaking with the actual owner, not a friend of the applicant.
- Step 2: Ask Targeted Questions: Inquire about rent punctuality, property damage, and whether the tenant moved out voluntarily or after a filing was initiated.
- Step 3: Confirm Re-Leasing Status: The most telling question is: "Would you rent to this person again?"
Before making any decision, ensure your eviction screening process complies with the Fair Credit Reporting Act (FCRA) and fair housing laws. Always apply the same screening standards to every applicant, document adverse action decisions, and rely on verified data rather than assumptions.
How to Avoid Evictions in the Future?
Moving into a new rental after an eviction is a genuine fresh start. Protecting it means understanding which situations lead to another filing before they arise.
- Contact your landlord the moment a payment problem appears. Eviction proceedings rarely start overnight. Most landlords would rather work out a payment plan than incur the costs and time of a court filing. An honest conversation before you miss a payment gives you far more options than one made after.
- Read your lease for the clauses that most commonly cause disputes. Unauthorized occupants, unapproved pets, and subletting without written permission are among the most frequently cited lease violations, aside from nonpayment. Go through those sections carefully when you move in, not after a dispute has already started.
- Know your tenant rights for your state before you need them. The U.S. Department of Housing and Urban Development publishes tenant rights information for every state at hud.gov. If you receive any notice from your landlord, look up your local rules before you respond. Many tenants lose protections simply because they did not know those protections existed.
- Use financial assistance programs before you fall behind. The 211 hotline connects callers to local rent assistance, utility help, and emergency housing funds. FindHelp.org lets you search for aid programs by ZIP code in your area. Reaching out at the first sign of financial pressure keeps a rough month from becoming a court record.
Fair Housing: Legal Questions to Ask About a Past Eviction
When a rental application reveals a past eviction, landlords often want to ask follow-up questions. Some are fully permitted. Others trigger Fair Housing violations regardless of how they are worded. The line sits between questions tied to rental qualifications and questions that touch a protected class under the Fair Housing Act.
Denying an application based on eviction history also requires sending an adverse action letter, here's what it must include to stay FCRA-compliant.
The table below covers the most common questions landlords ask when an eviction surfaces during screening.
One risk landlords often overlook: a question does not need to be overtly discriminatory to create legal exposure. HUD has issued guidance cautioning that blanket policies automatically denying applicants with any prior eviction record can violate fair housing law due to the disparate impact they produce on applicants from protected classes.
The law looks at outcomes, not just intent. When an eviction comes up during screening, stick to the questions in the left column, document your process, and apply the same standard to every applicant.
For the full framework of legally defensible screening decisions, see valid reasons to deny a rental application under fair housing law.
How to Rent Again After an Eviction?
An eviction on your record makes the next application harder, not impossible. These steps give you the best chance of getting approved.
- Step 1: Settle any outstanding debt first. Contact your previous landlord or the collection agency handling the debt and pay off what you owe. Some landlords will accept a settlement letter as proof of resolution, which strengthens your position before you apply anywhere.
- Step 2: Pull your own screening report. Know what a landlord will see before they see it. Check your court records and credit report for inaccurate entries, and dispute anything that does not reflect the actual outcome of your case.
- Step 3: Check if your record qualifies for sealing or expungement. In some states, dismissed eviction cases or COVID-era filings can be removed from public records. Contact the court clerk in the county where the case was filed to find out what options your state allows.
- Step 4: Prepare a short, honest explanation. Landlords will ask what happened. Acknowledge the eviction, explain what has changed since, and keep it factual. A calm, direct account is more convincing than no explanation at all.
- Step 5: Gather strong references before you apply. Ask previous landlords, employers, or colleagues who can speak to your reliability. A letter from someone who has seen you handle financial or rental responsibilities carries real weight with a cautious landlord.
- Step 6: Offer a larger security deposit or prepay one month's rent. This reduces the landlord's perceived risk without requiring them to waive their criteria. Many private landlords will consider this in place of a stricter credit requirement.
- Step 7: Target private landlords over large property management companies. Individual owners have more flexibility in their screening decisions. Some do not run a formal background check at all, which means your full application gets evaluated rather than filtered by an automated system.
- Step 8: Get a cosigner if your application is still weak. A creditworthy family member or close contact who cosigns your lease gives the landlord a fallback if anything goes wrong. This is one of the most effective ways to get approved when your record is the main obstacle.
For the complete strategy on navigating the rental market after an eviction, see our full guide on renting with an eviction on your record.
LeaseRunner: All-in-One Tenant Background Screening Service
When an applicant discloses a prior eviction, organized data makes the screening decision cleaner. LeaseRunner brings eviction checks, credit reports, and criminal background searches into one dashboard.
Every search runs through a nationwide database covering over 36 million records. Applicant consent is collected before any report is pulled, so you never need to ask for sensitive information directly. Here is how the eviction check process works:
- Create a free account at leaserunner.com. There is no cost until you run a report.
- From your dashboard, select "Screen" and choose "Eviction Check" along with any other reports you need.
- Enter the applicant's name and email address. LeaseRunner contacts them directly to collect consent and verify their identity.
- Once the applicant consents, the search runs across all major jurisdictions. Results appear in your dashboard alongside the applicant's other screening data.
Every applicant moves through the same workflow. That keeps your process consistent and documented, which matters if a denial decision is ever challenged.
Bottom Line
Overall, tenant screening doesn’t have to be complicated. By checking eviction history along with credit reports, you can make better, more informed choices. Knowing how to check eviction history is key, and tools like LeaseRunner make it easy by providing quick access to all the essential tenant reports in one place!
FAQs
Q1: How to find out if I have an eviction?
To find out if you have an eviction on your record, you can check your public court records or tenant screening reports. You can search online court databases in the county where you lived, or request a copy of your eviction record from the courthouse. Additionally, you can use tenant screening services to run a background check that includes eviction history.
Q2: Where to find eviction records?
Eviction records are part of public court records and can usually be accessed through local government websites or directly at the courthouse. Many screening platforms will show you a tenant’s eviction history, including filing dates, reasons for eviction, and case outcomes.
Q3: Can I Remove or Dispute an Eviction Record?
Yes, tenants may have options to remove or dispute eviction records, but the process depends on whether it’s a filing or a judgment, and on state-specific laws. Some states allow eviction records to be sealed or expunged, especially if the case was dismissed. Records usually stay for up to 7 years.
Q4. Do Evictions Show Up on Credit and Background Checks?
Yes, they can show up on both, but they appear in different ways. This is a crucial distinction that can surprise many tenants. Landlords often ask how do landlord check for evictions, and the answer is that filings may appear in public records, while judgments typically show up on credit reports and background checks for up to 7 years.
Q5. How do I check eviction history by address?
You can search eviction history by address through county or housing court case search portals where the property is located. Results vary by jurisdiction, and many courts still require searching by tenant name rather than address alone.
Q6. Are eviction records public in the US?
Yes. In most U.S. states, eviction filings are public court records, though access rules and online availability vary by state and county.
Q7. Do eviction filings show up in public court databases?
Yes. Eviction filings usually appear in civil or housing court databases, even if the case was later dismissed or resolved.
Q8. What information do I need to search eviction court records?
Typically, you need the tenant’s full legal name and the county or state where the rental property was located. Prior addresses and date ranges improve accuracy.
Q9. How long do eviction records stay public?
Eviction records can remain public for several years, often 7 years or longer, depending on state law, court retention rules, and whether the record is sealed or expunged.
Q10. Does winning an eviction case remove it from your history?
No. Winning or dismissing an eviction case does not automatically remove the record. The filing may still appear unless the court seals or expunges it under state law.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.