A tenant credit check is one of the most important tools landlords use to evaluate rental applicants and reduce financial risk. While credit scores often receive the most attention, a credit report also reveals valuable information about payment history, debt levels, collections, bankruptcies, and overall financial responsibility.
So, what do landlords look for in a credit check? This guide explains the key factors landlords review, common red flags to watch for, and best practices for conducting tenant screening. We'll also cover the difference between soft and hard credit inquiries and how LeaseRunner helps landlords run credit checks quickly and securely.
Quick Facts About Things Landlords Look For In a Credit Check
What Is a Rental Credit Check?

A rental credit check is an essential tool for landlords to assess a prospective tenant's financial responsibility, creditworthiness, and reliability, as well as confirm their identity through a process called identity verification. It provides a detailed report on your financial background, including your credit score, payment history, debt, and public records like bankruptcies or past evictions.
Landlords use this information to determine if you are a low-risk tenant who will pay rent reliably and on time. One or more of the three main credit bureaus, Experian, Equifax, and TransUnion, produce the credit report. Every bureau may have somewhat different data, hence landlords occasionally review more than one report.
LeaseRunner credit checks in the tenant screening process offer comprehensive credit reports that feature the VantageScore 3.0, along with details on addresses, employment (if available), and any liens, bankruptcies, or judgments.
What Do Landlords Look for in a Credit Check?
As part of the tenant screening process, a credit check is an essential tool for landlords. It helps them predict a prospective tenant's financial responsibility and reliability. For landlords, understanding a tenant’s creditworthiness helps them minimize risk and protect their investment.
For tenants, knowing the landlord's credit check criteria helps them prepare their application and present themselves in the best possible light. A credit report provides a detailed view of a person’s financial history, revealing far more than just a single number. Landlords use this information to determine if an applicant can handle the financial commitment of a lease and make timely rent payments.
To simplify the process, here is a quick breakdown of the primary factors landlords evaluate during a screening:
1. Credit Score
The first thing landlords look at is your credit score. This number, a product of your financial history, serves as a quick snapshot of your credit risk. Many landlords set a minimum credit score requirement for renting, often in the range of 600-620. As your score increases, so do your chances of being approved.
Scores above 700 are generally considered good credit scores and can make an application stand out. However, remember that the credit score is just one part of the equation, as landlords use a more holistic landlord credit report analysis for a final decision.
This analysis often considers the full range of credit scores, from poor to excellent, to determine a renter's eligibility, and they may also look at a specific credit score type, like FICO or VantageScore, to standardize their evaluations.
2. Payment History
Landlords will closely scrutinize your payment history for evidence of consistent payments. This is one of the most significant factors that affect a credit score of a tenant’s future behavior. Red flags include late payments, defaults, or accounts in collections (for example, unpaid medical bills or credit card debt sent to a collection agency).
While one or two late payments may not be a deal breaker, a pattern of missed payments will almost certainly result in a rejected application. A history of consistent, on-time payments on past loans and credit cards shows a clear pattern of responsible financial behavior, which is exactly what a landlord wants to see.
3. Debt-to-Income Ratio
Debt-to-income, or DTI, is a crucial metric that compares your monthly debt load to your income. Landlords want to know that your income will be sufficient to pay your bills and your rent, and they may ask for bank statements to verify this.
While the traditional banking system sets a strict 36% benchmark for residential mortgages, independent landlords and property managers typically establish a more practical 40% cutoff threshold for rental housing.
A DTI ratio higher than 40% signals severe financial strain and serves as a major red flag during tenant screening. For example, if an applicant earns $4,000 per month and their combined monthly debt liabilities, including the target rent—total $1,800, their DTI sits at 45% ($1,800 / $4,000). Experiencing a DTI over the 40% limit indicates that the applicant is financially overextended, making them a high-risk candidate for rental delinquency.
4. Public Records (Bankruptcies and Judgments)
Public records on your credit report are among the most serious financial red flags for landlords. These are typically a result of severe financial distress and often lead to an application being denied.
- Evictions: A past eviction is a major concern as it indicates a previous failure to uphold a rental agreement.
- Bankruptcies: A bankruptcy shows a history of significant financial failure. While it may not automatically disqualify you, it will require a more thorough explanation and a strong case for your current stability.
- Civil Judgments: These are court-ordered debts that you have failed to pay. They show a clear history of not meeting financial obligations and are viewed very negatively.
- Tax Liens: Similar to civil judgments, these are government-issued claims against your property due to unpaid taxes, showing a clear history of not meeting financial obligations.
5. Credit utilization
Credit utilization refers to the amount of credit you are using compared to your total available credit. For example, if you have a credit card with a $10,000 limit and you have a balance of $8,000, your credit utilization is 80%. A high percentage can indicate that you rely heavily on credit, which may concern a landlord.
A low credit utilization ratio (typically below 30%) suggests good financial management and is seen as a positive sign. Managing this ratio is one of the effective tips on how to pass a rental credit check.
6. Length of Credit History
The length of your credit history shows how long you've been managing credit. Landlords see a longer history as a good thing because it provides a more comprehensive view of your financial habits.
If you have a short credit history, such as a recent college graduate with only a few months of credit card use, a landlord may not have enough information to make a confident decision. In such cases, having a co-signer or a strong rental history from a previous landlord can help make up for a limited credit history.
Bringing in a financially responsible apartment rental cosigner allows the landlord to evaluate a more established credit profile alongside your own application.
7. Credit Inquiries
Credit inquiries are records of when a lender or other entity has checked your credit report. They are divided into two types: soft and hard inquiries. A hard credit check, like the one a landlord performs as part of the landlord's credit report checklist, can slightly lower your credit score.
Many hard inquiries in a short period might signal to a landlord that you are in a difficult financial position and are desperately seeking new credit.
How LeaseRunner Helps Landlords Run Rental Credit Checks
Reviewing a credit report is only one part of the tenant screening process. Landlords also need to verify an applicant’s identity, evaluate financial stability, compare income against debt obligations, and apply screening standards consistently across all applicants.
LeaseRunner simplifies this process by providing access to comprehensive tenant screening reports through its tenant screening platform. Landlords can order a tenant credit report to review payment history, outstanding debt, credit utilization, account status, and bankruptcy information when reported. LeaseRunner credit reports include Experian credit data and VantageScore 3.0, giving landlords a more complete view of an applicant’s financial profile.
To help reduce application fraud, LeaseRunner also includes identity verification tools that confirm applicant information before screening reports are generated. This allows landlords to verify that the credit data belongs to the person applying for the rental.
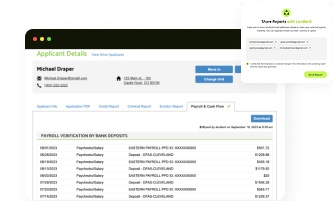
Credit information should never be reviewed in isolation. Landlords can combine credit data with income verification and cash flow reports, rental history, and other screening criteria to better evaluate whether an applicant can comfortably afford the rent. This helps create a more complete and consistent screening process.
For landlords who want a more standardized approach, LeaseRunner centralizes credit reports, identity verification, eviction records, income verification, and other screening tools in one dashboard. By reviewing the same screening criteria for every applicant, landlords can streamline decision-making, reduce manual screening errors, and make more informed leasing decisions.
What Credit Score Do Most Landlords Require?
A rental application credit check is a formal financial screening process used to verify a prospect's creditworthiness before a lease is signed. The core components of this rental application credit check include a credit score, payment history, debt levels, bankruptcies, and collections. While requirements vary by market, a score in the 670–739+ range is widely considered the “gold standard" for immediate approval. This check serves as the ultimate benchmark for a landlord's peace of mind and a tenant's negotiation leverage.
While there is no universal “passing grade" for renting, the specific requirement often depends on the competitiveness of the local market and the individual landlord’s risk tolerance. Most landlords and property management companies prioritize the following tiers:
- The “Safe" Zone (670+): A score of 670 or higher is generally considered “good" and will qualify you for most standard apartments. In highly competitive urban markets (like New York City or San Francisco) or for luxury rentals, landlords may expect a score of 700 or above.
- The Baseline (600–650): This is the most common minimum requirement for mid-range apartments. Applicants in this range are usually approved, though some landlords may request additional proof of income.
- The Challenging Zone (Below 600): Scores below 600 are often viewed as "high risk." While not an automatic disqualification, you will likely need to strengthen your application with a co-signer, a larger security deposit, or proof of significant savings to get approved.
It is important to note who is reviewing your application. Large property management companies often use automated screening software with rigid cut-off points (e.g., automatically rejecting anyone under 620). In contrast, private independent landlords are often more flexible; they are more likely to look at the “whole picture", such as your rental history and current income, rather than rejecting you solely based on a number.
Why Do Landlords Use Credit Checks?
Rental credit checks or credit checks before a lease help landlords lower their chances of experiencing issues like unpaid rent or property damage. A high credit score generally indicates a history of wise money management and paying bills on time. Conversely, a low credit score may suggest missed payments, significant debt, or other financial difficulties.
This makes landlords concerned about a tenant's potential for irregular rent payments. Therefore, understanding what landlords look for in a credit check clarifies how they will view your application and how you can raise your chances of being approved.
Landlords use the tenant screening process to assess a prospective tenant's financial responsibility and creditworthiness. The landlord credit report analysis provides a comprehensive view of an applicant's financial behavior.
Understanding the key landlord credit check criteria is essential for any renter. To improve your odds, it’s smart to check your own credit report for errors, pay down existing debt, and address any accounts in collections before applying. Knowing what credit score is needed to rent an apartment is another way to set your expectations correctly.
By addressing these issues beforehand, you can present yourself as a reliable, financially stable applicant. For more tips on how to pass a rental credit check, check out our detailed guide. Landlords often use professional services for a thorough tenant financial screening criteria check.
What Credit Score Do Landlords Typically Accept?
There is no universal minimum credit score requirement for rental applicants. Credit score standards vary based on the property, local market conditions, and the landlord's screening criteria.
Many landlords view scores of 670 or higher as a strong indicator of creditworthiness, while applicants in the 600–669 range may still qualify when supported by stable income, positive rental history, or other compensating factors.
While there is no single rental credit score requirement that applies to all properties, most landlords have a preferred range. A good credit score is often considered to be above 670, and a tenant in this range is typically seen as a low-risk applicant.
For instance, an applicant with a lower score but a stable job and a history of paying rent on time may be seen as a better bet than someone with a high score but a sporadic work history.
If your score is on the lower side, you should be prepared to provide additional information, such as proof of income and credit references, on your rental application. Sometimes, providing a credit report for renters from a reputable source can also help you show your financial standing clearly. You can also strengthen your application by including what credit references are on the rental application. This provides landlords with an even more comprehensive picture of your financial background.
LeaseRunner Rental Screening Science Score (RS³)
Traditional credit checks remain an important part of tenant screening, but they do not always tell the full story. A credit report reflects past borrowing behavior, while many rental decisions depend on a tenant’s current ability to afford rent and manage cash flow. This is where LeaseRunner’s Rental Screening Science Score (RS³) provides additional insight.
RS³ is LeaseRunner’s proprietary scoring model designed specifically for rental screening. Instead of relying on credit history, RS³ evaluates applicant risk using verified bank income, cash flow stability, and rent-relative affordability. By analyzing actual financial activity, the score helps landlords assess whether an applicant can realistically support the monthly rent based on their current financial situation.
One of the biggest advantages of RS³ is that it can provide meaningful screening insights for applicants who have limited credit history, thin credit files, or credit profiles that may not fully reflect their present financial strength. This allows landlords to look beyond traditional credit metrics and make more informed leasing decisions.
For landlords, RS³ helps reduce reliance on a single screening factor and provides an additional data point when comparing applicants. By incorporating verified income and cash flow information, landlords can better identify financially stable tenants, reduce screening uncertainty, and lower the risk of approving applicants who may struggle to meet ongoing rent obligations.
For applicants, RS³ offers a more comprehensive evaluation process because it considers real-world financial capacity rather than focusing solely on past credit usage. This can create a fairer screening experience for qualified renters whose credit scores may not accurately represent their ability to pay rent consistently.
When used alongside credit reports, identity verification, income verification, and rental history reviews, RS³ helps landlords build a more complete picture of applicant risk and make better-informed tenant selection decisions.
Best Practices in Credit Checks for Landlords
For landlords, implementing a solid tenant screening process is essential for making informed decisions. While the credit report is a critical piece of the puzzle, it must be viewed within the broader framework of your screening criteria. Landlord screening criteria are the set of objective standards used to evaluate applicants, encompassing income requirements, credit thresholds, criminal history, and past rental performance.
The most important aspect of these criteria is that they must be applied consistently to every applicant to ensure compliance with Fair Housing laws. Having these criteria in writing before the first application arrives protects you from claims of discrimination while streamlining your decision-making. Here are some best practices for landlords when evaluating a credit report for rental applications:
- Maintain Consistency: Apply your landlord screening criteria to all applicants without exception. Using a universal standard for credit scores or income levels is your best defense against accusations of bias.
- Review the full report, not just the score: The credit score is a good starting point, but a thorough landlord credit report analysis involves looking at the entire report. A high score with a recent eviction on the record should be a red flag, while a low score with a brief history and no negative marks may be acceptable.
- Verify the applicant’s identity: Ensure that the credit report belongs to the person applying. This helps prevent fraud.
- Look for patterns, not isolated incidents: A single late payment from five years ago is not as concerning as a series of recent missed payments. Focus on recent behavior to predict future reliability.
- Communicate your criteria: Make your rental credit score requirements clear in your listing or on the application. This saves time for both you and the applicant.
How Landlords Should Run a Rental Credit Check
Running a rental credit check involves more than simply reviewing a credit score. To make fair, consistent, and informed leasing decisions, landlords should follow a structured screening process.
Step 1: Establish Written Screening Criteria Before Accepting Applications
Before marketing a property, create clear tenant screening criteria that outline the standards applicants must meet. These may include income requirements, rental history expectations, credit standards, and other lawful screening factors. Having written criteria in place helps ensure consistency and supports compliance with applicable federal, state, and local fair housing laws.
Step 2. Obtain Written Consent Before Running a Credit Check
Landlords must obtain the applicant's authorization before accessing consumer credit information. Under the Fair Credit Reporting Act (FCRA), tenant screening reports can only be obtained for a permissible purpose and with proper consent from the applicant. Be sure to keep authorization records as part of your screening documentation.
Step 3. Use a Secure Tenant Screening Platform
Avoid relying on screenshots, PDFs, or credit reports submitted directly by applicants, as these documents may be incomplete, outdated, or altered. Instead, use a professional tenant screening platform that obtains credit information directly from authorized data sources.
LeaseRunner allows landlords to request tenant-authorized credit reports and screening reports through a secure online process. This helps ensure the information being reviewed is current, accurate, and obtained through compliant screening procedures.
Step 4. Review Credit Data Alongside Other Screening Factors
A credit report should be only one part of the evaluation process. Landlords should also verify identity, review income documentation, evaluate rental history, and assess overall financial stability.
Using LeaseRunner, landlords can combine credit reports with identity verification, income verification, and additional tenant screening tools to gain a more complete picture of an applicant's qualifications. Looking at multiple data points often provides a more reliable assessment than relying on a credit score alone.
Step 5. Apply the Same Standards to Every Applicant
Consistency is essential during tenant screening. Once screening criteria have been established, they should be applied uniformly to all applicants for the same property. Using different standards for different applicants can increase legal risk and create potential fair housing concerns.
By following a consistent process and using reliable screening data, landlords can make better-informed leasing decisions while reducing the risk of overlooking important information during applicant evaluations.
Wrap Up
A credit report provides valuable insight into an applicant's financial history, but it should never be evaluated in isolation. Landlords should review credit scores, payment history, debt obligations, bankruptcy records, income verification, identity information, and rental history together to make well-informed leasing decisions.
To streamline the process, use LeaseRunner’s full suite of tenant screening reports. Early on, check your credit; correct mistakes, lower debt, and provide income verification. These actions will allow you to find your future house with ease.
FAQs
Q1. Do private landlords do credit checks?
Indeed, although not always, many private landlords do credit checks. Others depend on referrals or firsthand interviews. To lower risk, nevertheless, credit checks are becoming increasingly routine among private landlords.
Q2. What is the relation between credit score and apartment renting?
When renting an apartment, your credit score plays a big role. Apartments often have minimum credit score requirements. If your score is low, you may need to provide extra documentation or a co-signer.
Q3. What happens if you fail a rental credit check?
If you fail, landlords might turn down your application. You may attempt to correct problems and get comments. Sometimes, giving a bigger co-signer or deposit helps.
Q4. What credit score ranges do landlords prefer?
Most landlords desire renters with credit scores higher than 600. Good and often approved scores are between 670 and 739. Very excellent scores above 740 help to simplify the approval process. If your score is poor, landlords might demand a co-signer or a larger deposit.
Q5. What kind of credit score are landlords looking for?
While requirements vary by location and property type, most landlords look for a score of 670 or higher, which is considered “good" and indicates a low risk. Scores between 600 and 650 are often acceptable but may require extra proof of income or a higher deposit. In highly competitive markets or for luxury apartments, landlords often prefer scores above 700.
Q6. What are red flags on tenant credit reports?
Landlords view prior evictions and active bankruptcies as the most serious red flags, as they suggest a high risk of lease violation. Other major warning signs include civil judgments (court-ordered debts), accounts in collections (especially for utilities or previous rent), and a recent history of late payments. A high Debt-to-Income (DTI) ratio is also a concern, as it indicates the tenant may be overextended financially.
Q7. How much income proof is needed for renting?
The industry standard is the “3x Rent Rule," meaning your gross monthly income should be at least three times the monthly rent. To prove this, landlords typically require 2–3 recent pay stubs, a W-2 form, or an employment verification letter. If you are self-employed or a freelancer, you will likely need to provide two years of tax returns and 3–6 months of bank statements to verify consistent earnings.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.