It’s easier to rent a home when you understand not just how to pass a rental credit check, but also how to pass tenant screening as a whole. This guide breaks it all down—what landlords check, how to boost your profile, and how to stay ahead in the process so you can improve your chances of rental credit approval.
What Is a Rental Credit Check?
A rental credit check is a key part of the tenant screening process. Landlords use it to get a quick picture of how someone handles money, particularly when it comes to paying bills on time. It plays a major role in rental credit approval decisions.
For tenants, this check is a chance to make a strong first impression. A solid credit history shows you’re responsible, while credit issues might raise red flags. But even with a bad score, learning how to pass a rental credit check — and understanding tenant credit requirements — can help you get approved.
Can You Pass a Rental Credit Check with Bad Credit?
Yes, it is possible to pass a rental credit check with bad credit. While many landlords review credit reports as part of tenant screening, a low credit score does not automatically mean your application will be denied.
Most landlords evaluate the entire rental application rather than relying on a single number. They may consider factors such as your income, employment stability, rental history, debt obligations, and references from previous landlords. A strong overall application can often offset credit challenges, especially if the negative marks resulted from a temporary financial hardship rather than ongoing payment problems.
Applicants with lower credit scores can improve their chances of approval by providing proof of stable income, demonstrating a history of on-time rent payments, supplying positive landlord references, or applying with a qualified co-signer or guarantor. In some states, landlords may also accept a larger security deposit or prepaid rent where permitted by law.
The reason behind the credit issues also matters. For example, landlords may view isolated medical debt, a past job loss, or older collection accounts differently from recent missed payments, active collections, or repeated financial problems. Showing evidence that your financial situation has improved can help build confidence in your application.
What Do Landlords Check in a Rental Credit Report?
Before applying for a rental, it helps to understand which parts of your credit report may attract the most attention during tenant screening. Reviewing these items ahead of time can help you fix problems, prepare supporting documents, and improve your chances of approval.
Payment History
Late payments, charge-offs, and collection accounts are often among the first items landlords review. Recent negative marks typically carry more weight than older issues that have already been resolved.
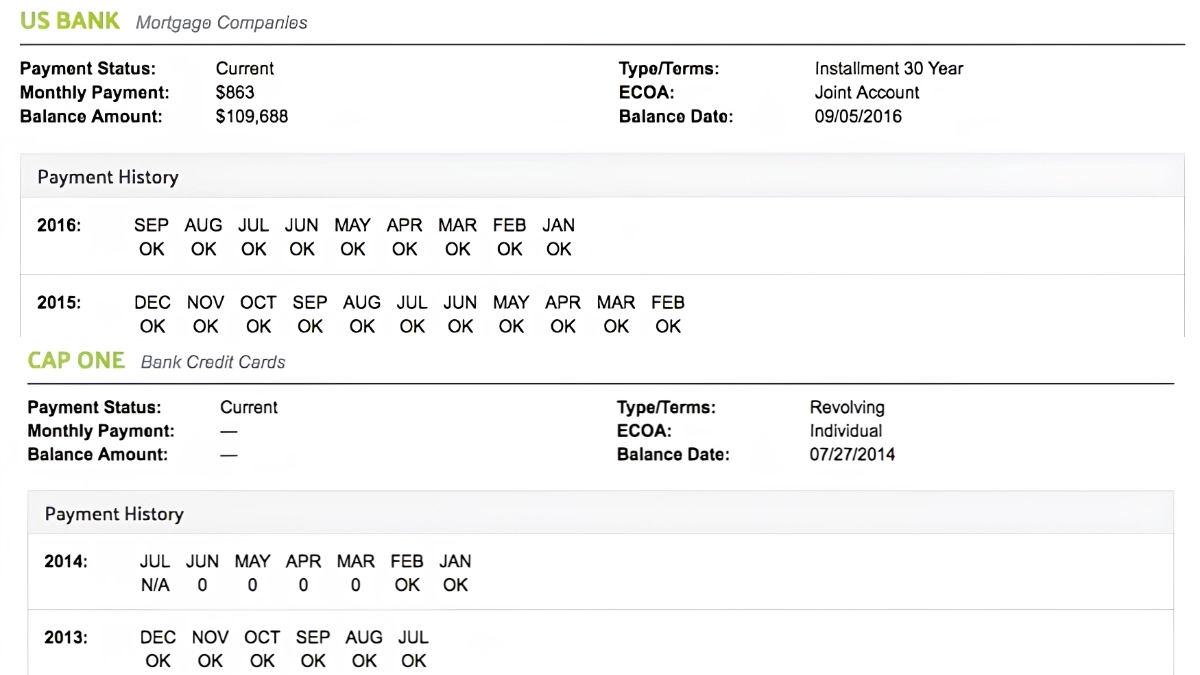
What to check:
- Recent late payments
- Accounts in collections
- Unpaid debts
- Reporting errors that should be disputed
Credit Score and Overall Credit Profile
Your credit score is only one part of the screening process, but it can influence a landlord's decision. Different properties may have different requirements, and many landlords review the full credit profile rather than relying solely on a score. Learn more about what credit score is needed to rent an apartment.
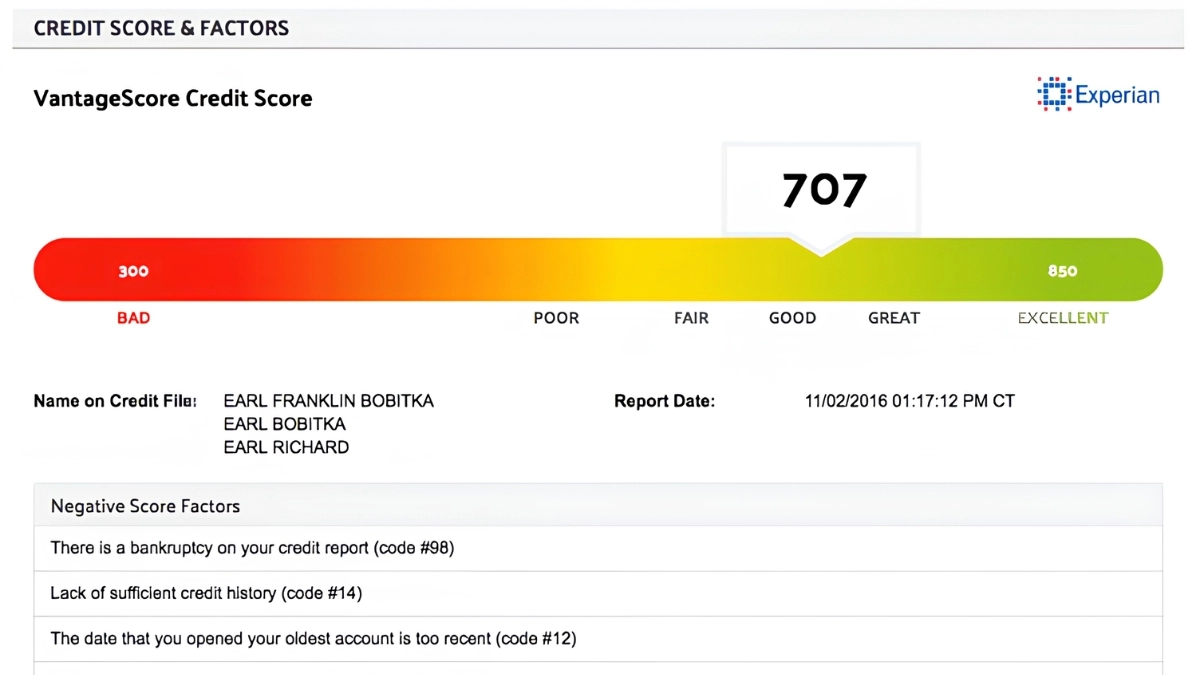
What to check:
- Your current credit score
- Recent negative accounts
- Credit utilization levels
- Any unexplained credit inquiries
Outstanding Debt
Landlords may review your existing financial obligations to determine whether your income can comfortably support the monthly rent.
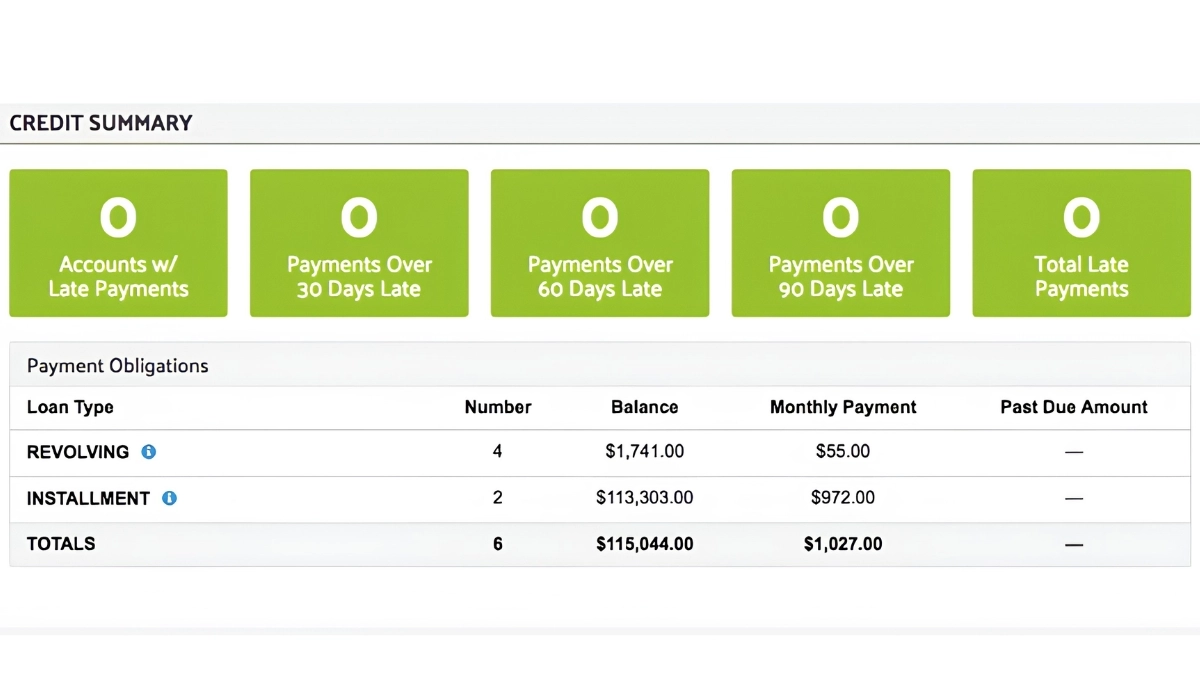
What to check:
- High credit card balances
- Significant monthly debt payments
- Recently maxed-out accounts
- Opportunities to reduce debt before applying
Rental-Related Records
Past rental issues can sometimes affect tenant screening results. This is why accurate rental history is important when applying for housing. Learn more about what rental verification is and how landlords verify an applicant's rental history.
What to check:
- Previous rental debts
- Eviction-related records where legally reportable
- Incorrect rental history information
- Outstanding balances owed to former landlords
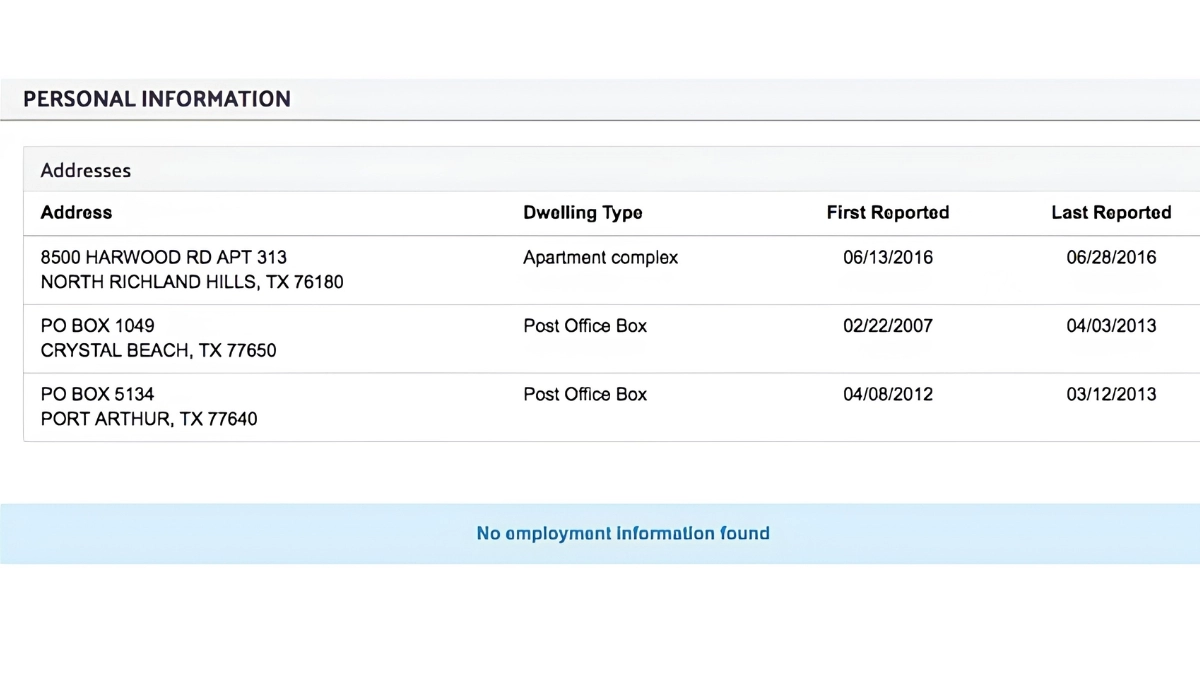
Personal Information Accuracy
Errors in your personal information can cause delays or create confusion during screening.
What to check:
- Name and date of birth
- Current and previous addresses
- Employment information
- Accounts that do not belong to you
Income and Financial Stability
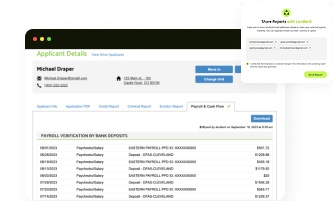
Credit reports are only one part of tenant screening. Many landlords also review income, employment, and financial stability when evaluating applications. Services such as income verification and cash flow reports may be used to confirm an applicant's ability to afford rent.
Before applying, prepare:
- Recent pay stubs
- Bank statements if requested
- Employment verification documents
- Positive landlord references
If you'd like to see what information landlords commonly review during screening, you can also review a professional rental credit check report before submitting applications.
Reviewing your credit report before applying gives you time to correct mistakes, resolve outstanding issues, and prepare explanations for any negative items that may appear during tenant screening.
How to Pass a Rental Credit Check
Passing a rental credit check can feel intimidating, but with preparation, you can increase your chances of getting approved. Here’s a detailed breakdown of practical steps tenants can take:
1. Check Your Credit Report in Advance
Landlords base rental decisions on the information in your credit report. Errors, outdated collections, or duplicate accounts can unfairly lower your score and hurt your approval chances. Reviewing your report early gives you time to correct mistakes before a landlord sees them.
What to do:
- Request free reports from Equifax, Experian and TransUnion.
- Review payment history, balances, and public records carefully.
- Dispute inaccurate late payments or duplicate accounts immediately.
- Verify that paid collections or settled debts are reported correctly.
Even small corrections can raise your score and improve your rental application.
2. Pay Down Existing Debt
Credit utilization (how much of your available credit you’re using) heavily impacts your score. High balances signal financial strain, which may make landlords question whether you can afford rent alongside other obligations.
What to do:
- Pay credit card balances below 30% of each limit (ideally under 10%).
- Avoid opening new credit accounts right before applying.
- Focus on reducing revolving debt rather than installment loans first.
- Create a short-term payoff plan 1–3 months before applying.
Lower balances show financial control and improve your debt-to-income picture.
3. Make Timely Bill Payments
Payment history is the single largest factor in most credit scoring models, accounting for approximately 35% of your FICO® Score. Consistently paying bills on time helps build a stronger credit profile and demonstrates financial responsibility.
It is also important to understand how late payments affect your credit. A late rent fee charged by a landlord does not automatically appear on your credit report. In most cases, rent payments only affect your credit history if they are reported through a rent-reporting program or if an unpaid rental debt is later sent to a collection agency.
The impact of a reported late payment varies based on your existing credit profile. Applicants with excellent credit may experience a larger score decrease after a reported delinquency, while those with lower scores may see a smaller decline. Regardless of the exact number of points lost, recent delinquencies and collection accounts can make landlords view an application as higher risk during tenant screening.
What to do:
- Set up autopay for credit cards, loans, and utilities.
- Pay at least the minimum due before the due date.
- Catch up immediately on any past-due accounts.
- Avoid letting small bills go to collections.
Consistent on-time payments demonstrate reliability, which directly supports rental approval.
4. Provide Proof of Income and Employment
Even with average credit, strong income can offset risk. Most landlords require income 2..5 – 3 times the monthly rent. Stable earnings reassure landlords that rent will be affordable.
What to do:
- Pay stubs, tax returns, bank statements or an employment verification letter are the proof of income that can help prove stability.
- For freelancers or gig workers, providing bank statements or 1099 forms demonstrates reliable income. Be cautious of fake pay stubs, which landlords often spot.
5. Offer a Larger Security Deposit or Prepaid Rent
If your credit is borderline, landlords may worry about missed payments. Offering additional upfront funds reduces their financial risk.
What to do:
- Offer one additional month of security deposit (if legal in your state).
- Propose prepaying 1–2 months of rent.
- Clarify deposit terms in writing.
This strategy works especially well when your income is strong but your credit score is slightly below preferred thresholds.
6. Have Strong References
Credit shows financial behavior, but references show real-life rental behavior. Positive landlord references can offset minor credit issues. In fact, understanding what are credit references on a rental application can help you prepare stronger documentation that supports your rental credit approval.
What to do:
- Ask previous landlords to confirm on-time rent payments.
- Provide contact details for property managers.
- Include professional references if rental history is limited.
- Ensure references are responsive and aware they may be contacted.
Good references help landlords see the full picture, not just your credit report.
7. Write a Cover Letter Explaining Credit Issues
Landlords often look at patterns, not just numbers. If past credit problems were caused by temporary hardship, explaining recovery shows responsibility and growth.
What to do:
- Keep the letter short and factual.
- Explain the cause (e.g., job loss, medical bills).
- Highlight how the issue was resolved.
- Emphasize consistent payments since then.
Demonstrating financial recovery can improve trust and credibility.
8. Consider a Co-Signer or Guarantor
A co-signer or guarantor apartment with strong credit can reduce the landlord’s risk. This is common for students, young renters, or anyone with limited credit history.
What to do:
- Choose someone with strong credit and stable income.
- Ensure they understand legal responsibility.
- Confirm the property allows co-signers.
- Prepare their income and credit documentation in advance.
This option is common for students, first-time renters, or applicants rebuilding credit.
9. Use a Tenant Screening Service Beforehand
Knowing what landlords will see eliminates surprises. Reviewing your screening report allows you to prepare explanations or corrections in advance.
What to do:
- Using rent reporting services can also help build your score over time
- Review eviction and public record data.
- Confirm identity information is accurate.
- Bring a copy of your report when applying, if allowed.
Transparency and preparation can make a strong impression during the application process.
10. Maintain Financial Habits Beyond the Application
Passing a credit check isn’t just about one apartment. Strong financial habits make future rentals easier and may even improve lease terms.
What to do:
- Keep credit utilization low.
- Build an emergency savings fund (3–6 months of expenses).
- Avoid unnecessary hard credit inquiries.
- Continue paying all obligations on time.
This ensures stronger applications down the road and can even lead to better rental terms, such as a generous grace period on rent.
How to Prepare Before a Rental Credit Check
Preparing before a rental credit check gives you an opportunity to fix potential issues and present a stronger application. Taking a few simple steps in advance can help you avoid surprises during tenant screening and improve your chances of approval.
Check Your Credit Report in Advance
Before applying, review your credit reports to see exactly what landlords may see during screening. This allows you to identify negative items, outdated information, or accounts that need attention.
Pay special attention to payment history, outstanding debts, collection accounts, and rental-related records. Understanding these details can help you better prepare for questions that may arise during the application process.
You may also find it helpful to learn more about what landlords look for in a credit check before submitting rental applications.
Dispute Credit Report Errors
Credit reporting mistakes are more common than many renters realize. Incorrect late payments, duplicate accounts, inaccurate balances, or accounts that do not belong to you can negatively affect your application.
If you identify an error, submit a dispute directly with the credit bureau reporting the information. Because investigations can take time, it is best to review your reports several weeks before you plan to apply for housing.
Correcting inaccurate information may improve your credit profile and prevent unnecessary concerns during tenant screening.
Pay Down High Credit Card Balances
High credit card balances can make it appear that you are carrying significant financial obligations, even if you have never missed a payment.
If possible, reduce revolving credit card balances before applying. Lower balances can strengthen your overall credit profile and demonstrate responsible financial management.
Focus on reducing balances on accounts that are close to their credit limits, as these may attract additional scrutiny during the screening process.
Write a Short Explanation Letter
If your credit report contains negative information resulting from a temporary hardship, consider preparing a brief explanation letter.
Keep the letter factual and concise. Explain the circumstances, such as a job loss, medical emergency, or other financial setback, and describe the steps you have taken to resolve the issue. If your financial situation has improved, include supporting documentation when appropriate.
A clear explanation can provide valuable context and help landlords evaluate your application more fairly.
What Credit Score Do You Need to Rent an Apartment?
While there is no "universal" minimum, most professional property managers in 2026 use the following tiers to evaluate risk:
Note: Security deposit limits vary by state and, in some cases, by the type of landlord. For example, California's AB 12 generally limits security deposits to one month's rent for most residential tenancies. However, a limited exception allows certain small landlords—those who own no more than 2 residential rental properties with a combined total of 4 or fewer units—to collect up to two months' rent as a security deposit in many situations. New York and other states also impose their own deposit limits.
Because security deposit laws differ significantly by jurisdiction, renters should review their state's current requirements before offering a larger deposit. If deposit limits prevent additional upfront payments, strengthening your application with proof of income, positive rental references, savings documentation, or a qualified guarantor may improve your chances of approval.
Top Alternatives for Proving Reliability
If your credit score doesn’t tell the whole story, you need to provide "alternative credit" data. These documents act as a secondary safety net, proving to a landlord that you are a low-risk, responsible tenant regardless of your score.
- Strong Proof of Income: Provide recent pay stubs, tax returns, or bank statements showing consistent income deposits. Aim to demonstrate earnings at least 2.5–3 times the monthly rent.
- Stable Employment History: Show long-term employment with the same employer or steady work in the same industry. An employment verification letter adds credibility.
- Positive Rental References: Ask previous landlords to confirm on-time rent payments, lease compliance, and good property care.
- Larger Security Deposit (If Legally Allowed): Offering additional upfront funds reduces landlord risk and may offset credit concerns.
- Prepaid Rent: Paying 1–2 months of rent in advance can demonstrate financial responsibility.
- Co-Signer or Guarantor: A financially strong co-signer reassures landlords that rent will be covered if issues arise.
- Savings or Emergency Fund Proof: Showing healthy savings in your bank account proves you have a financial cushion.
- Utility or Phone Payment History: Provide statements showing consistent on-time payments for utilities, internet, or phone bills.
- Short Explanation Letter: Briefly explain past credit challenges and show evidence of financial recovery.
- Rent Reporting Services: If you’ve paid rent consistently in the past, use rent reporting tools that add positive payment history to your credit profile.
Conclusion
Now that you understand how to pass a rental credit check, it’s time to take action. Clean up what you can, get your paperwork ready, and go make your next move with confidence! By applying these strategies, you’ll not only know how to pass a rental credit check today but also in the future.
For more tips on renting smarter, see our guide on the apartment rental application process to put your improved credit profile to work.
FAQs
Q1. What credit bureau do apartments use?
Most landlords and property management companies check credit reports from one of the three major credit bureaus: Experian, Equifax, or TransUnion. Some may use only one, while others go through third-party tenant screening services that pull data from multiple bureaus. You typically won’t know in advance which one they’ll use, so it’s a good idea to review your reports from all three.
Q2. What do landlords look for in a credit report?
Payment history, credit score, outstanding debts, collections or charge-offs, and any past evictions or bankruptcies. Knowing these helps you plan how to pass a rental credit check. They’re essentially looking for signs that you’ll pay rent on time and manage your finances well.
Q3. Can I rent an apartment with bad credit?
Yes, you can still rent even with a low score. Many renters figure out how to pass a rental credit check by showing steady proof of income, providing strong rental references, using a co-signer, or offering a larger security deposit. These steps reassure landlords that you’re reliable despite past credit issues.
Q4. Do all landlords check your credit?
Not always. Smaller landlords or private owners might skip the credit check and focus more on your rental history, income, or references. However, most professional property managers do run credit checks as part of a standard background screening.
Q5. Which Credit Bureaus Do Landlords and Apartments Use?
Landlords and property managers typically check reports from one of the three major credit bureaus: Experian, Equifax, or TransUnion. Some tenant screening services pull data from all three to give a fuller picture. Because you usually won’t know in advance which bureau will be used, it’s best to review your credit reports from all three before applying.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.