Whether you're screening tenants or searching for a rental, understanding the rent-to-income ratios can help you make more informed financial decisions. This affordability metric shows how much of a tenant's gross income goes toward rent and is one of the most common tools landlords use during the screening process.
In this guide, you'll learn what landlords typically look for, how the 30% rule and 3x rent rule work, which benchmarks hold up across different markets, and where fair housing rules limit how a ratio can be used.
What Is a Rent-to-Income Ratio?
The rent-to-income ratio is the percentage of a tenant’s gross monthly income spent on rent. Landlords use it while screening potential tenants to check if they can realistically afford the rental costs. At the same time, tenants use it to check if their housing fits within their budget.
A good rent-to-income ratio is generally 30% or less of a tenant’s gross monthly income — a guideline often called the “30% Rule.” According to Chase Bank, this benchmark helps tenants leave enough room in their budget for essentials, savings, and emergencies. Landlords usually look for proof of income during the application process to confirm this ratio. Some also require tenants to earn at least 3x the rent as an extra safeguard.
Meanwhile, the U.S. Department of Housing and Urban Development (HUD) considers households spending more than 30% of their adjusted income on rent as rent-burdened, and those spending over 50% as severely rent-burdened. Although landlords typically use this standard during tenant screening, they may accept higher ratios—between 30% and 45%—if an applicant’s overall financial profile is strong and justifies flexibility.
Quick Facts Table About Rent/Income Ratio
The 30% Rule: A commonly cited guideline
The 30% rule is a frequent and straightforward memory aid for rent-to-income ratios. But the question is “Why should the proportion of income allocated to rent be 30%? The idea is simple—it leaves room for savings, daily expenses, and emergencies, while also giving landlords a quick way to judge if a tenant can reasonably afford rent.
There are a few variations on this rule:
- 2.5x Rent: In high-cost markets, some landlords lower the requirement to 2.5x income.
- 28–30% of Gross Income: Another version is to keep rent at or below 28–30% of gross monthly income.
Ratio guidelines and income multipliers are two sides of the same screening decision. If you’re setting a fixed minimum income for your listings instead of a percentage, this guide on apartment income requirements breaks down the standards applicants are expected to meet, from documentation to qualification thresholds.
Minimum Rent Requirements for Renting an Apartment
If you are a landlord, you may wonder, "How much should a tenant make to afford rent"? You can roughly estimate by tripling the rent. Landlords have to establish minimum income requirements so that tenants may pay their rent.
The most generally accepted ratio is that a tenant's gross monthly income should be between 2.5 and three times their rent. This enables landlords to assess candidates and lower the possibility of evictions or unpaid bills.
In certain affordable areas, however, landlords may accept a much smaller income multiplier, perhaps 2.5x. Still, the 3x rule is the industry benchmark as it keeps a balance between renter affordability and landlord protection.
How to Calculate Your Rent-to-Income Ratio?
The formula works in both directions. Divide rent by gross income to see where an applicant stands, or multiply the rent by your income requirement, typically 3x to set the minimum income for a listing.
For example, an applicant earning $6,000 per month applying for a $1,800 unit sits at exactly 30%, right at the standard benchmark, so they would qualify under the most common threshold.
Running the numbers for a real applicant? Use our rent-to-income ratio calculator to check a ratio, set a rent ceiling, or work out a 3x income requirement, including combined household incomes and Section 8 portions.
Many renters and landlords also prefer to view affordability on an annual basis. Using the standard 30% guideline (or the equivalent 3× rent rule), the table below shows the approximate annual income needed for different rent levels.
Keep in mind that these figures are general affordability benchmarks rather than legal requirements. In higher-cost markets, some landlords may accept income closer to 2.5× rent, while others may require more than 3× rent depending on the applicant's credit profile, debt obligations, and rental history.
Why Rent to Income Ratio Is Important?
For landlords, the rent-to-income ratio is a reliable tool for screening potential tenants. It helps assess whether applicants can realistically meet their rent obligations, lowering the risk of late or missed payments and ensuring a stable rental relationship. Combined with a credit check, it gives landlords a clearer picture of a tenant’s financial reliability. The ratio also supports smarter decisions when evaluating rental property cash flow and setting sustainable rental terms.
For renters, the ratio works as a budgeting guide. By following the 30% rule, tenants can avoid financial strain and balance rent with other expenses. This becomes especially important when dealing with rising housing costs, such as a month-to-month rent increase in California.
3 Key Factors Affects Rent-to-income Ratio
As a landlord, you know the numbers don’t always speak for themselves. Here are the biggest factors that influence how reliable a rent-to-income ratio truly is.
1. Income Level
Obviously, a tenant’s income is the most direct factor affecting their rent-to-income ratio. A tenant with higher income will naturally have a healthier rent-to-income ratio, making it less likely they’ll struggle to pay on time. But with lower-income tenants, sticking to the 30% rule or requiring them to find a roommate can make the arrangement more secure for you.
2. Rent Prices and Location
The rent-to-income ratio can look very different depending on where a tenant lives.
- Urban vs. Suburban: In high-cost cities like Toronto or Miami, tenants may spend 35–40% of their income on rent, with Miami reaching as high as 54.9%. Although these figures are well above the 30% rule, strong infrastructure and reliable public transit often help balance out the higher costs.
- Rural Areas: Conversely, living in a rural area like Knoxville, renters may spend as little as 8.2% of their income on rent. Many rural areas show a similarly lower rent-to-income ratio because housing demand is weaker and rents are cheaper
So whether a tenant is paying above or below 30%, that can still be alright. The 30% rule isn’t a standard for every case, especially in markets with rent-stabilized or rent-controlled regulations. As a landlord, being flexible and looking at the bigger picture will give you a clearer sense of tenant affordability.
Typical Rent-to-Income Ratios by Market Type
These figures are general market observations rather than legal requirements. There is no federal law that establishes a maximum rent-to-income ratio for private-market rentals.
As a result, a tenant exceeding the traditional 30% guideline may still be considered qualified, particularly in high-cost housing markets. Many landlords evaluate additional factors such as credit history, debt obligations, employment stability, available savings, and rental history before making a final leasing decision.
The key takeaway is that the 30% rule serves as a useful benchmark, not a universal standard. Understanding local market conditions often provides a more accurate picture of tenant affordability than relying on a single percentage alone.
3. Other Financial Obligations
A clean rent-to-income ratio doesn’t always guarantee a tenant can comfortably afford your property. Debts like student loans, car payments, or credit card balances can stretch their budget thin. Family responsibilities or big savings goals can also limit what they can realistically pay each month. For landlords, this is why pairing the ratio with a credit check or reviewing additional financial details is so important.
Rent-to-Income Ratios: Guidelines and Alternatives
What If the 30% Rule Doesn’t Fit?
The rent-to-income ratio is a handy starting point, but it doesn’t tell you everything about a tenant’s finances. To really see the bigger picture, landlords can lean on a few alternative considerations alongside it:
DTI vs Rent-to-Income Ratio: What’s the Difference?
Although the rent-to-income ratio and debt-to-income (DTI) ratio are both affordability metrics, they measure different aspects of a tenant's finances.
- The rent-to-income ratio focuses only on housing costs. It shows what percentage of a tenant's gross monthly income would go toward rent.
- The debt-to-income ratio takes a broader view. It measures how much of a person's gross monthly income is already committed to recurring debt obligations, such as credit card payments, auto loans, student loans, and other recurring debts.
For example: Assume an applicant earns $6,000 per month before taxes and is applying for a rental that costs $1,800 per month. Their monthly debt obligations include a car payment ($350) and a student loan ($250).
- Rent-to-income ratio: ($1,800 ÷ $6,000) × 100 = 30%
- Debt-to-income ratio: (($1,800 + $350 + $250) ÷ $6,000) × 100 = 40%
In this example, the applicant meets the traditional 30% rent-to-income guideline. However, their DTI ratio shows that 40% of their gross income is already committed to housing and debt payments.
Section 8 / HCV Implications for Rent-to-Income Ratio
The traditional rent-to-income ratio works differently when a tenant participates in the Housing Choice Voucher (HCV) Program, commonly known as Section 8.
Under the program, a local Public Housing Authority (PHA) pays a portion of the rent directly to the landlord, while the tenant is responsible for the remaining share. Because voucher assistance reduces the tenant's out-of-pocket housing costs, the standard rent-to-income ratio may not provide a complete picture of affordability.
With a voucher in place, the tenant's own obligation is only their share of the rent — so screen affordability against that share, not the full contract amount.
What Should Landlords Consider?
When screening voucher applicants, landlords often review:
- The tenant's required portion of the rent
- Voucher approval and payment information
- Income verification
- Credit and rental history
- Background screening, where permitted by law
Rather than focusing exclusively on the full rent amount, many landlords assess whether the tenant can reliably pay their share of the rent and comply with the lease terms.
Fair Housing and Source-of-Income Considerations
Housing Choice Voucher holders are protected under certain state and local source-of-income laws. In jurisdictions with these protections, landlords may be required to consider voucher assistance as a lawful source of income and may not reject applicants solely because they use rental assistance.
Because source-of-income protections vary by state and locality, landlords should review applicable laws before establishing screening criteria for voucher applicants.
Is the 3× Rent Rule Still Used for Section 8 Tenants?
Not always. Some landlords apply their standard income requirements to the tenant's portion of rent rather than the full contract rent. Others may use alternative affordability measures that take voucher assistance into account.
As a result, the traditional 3× rent rule may be less relevant for voucher holders than for market-rate tenants. A more accurate approach is to evaluate the tenant's actual financial responsibility, overall stability, and rental history alongside any voucher assistance they receive.
Common Mistakes to Avoid When Using Rent-to-Income Ratios
If you’ve been using the rent-to-income ratio but still struggle with late payments or unreliable tenants, chances are you might be running into a few common mistakes.
Using Net Instead of Gross Income
One of the most frequent mistakes is calculating the ratio based on net income rather than gross income. Since net income excludes taxes and deductions, it understates affordability and can make tenants look less qualified than they actually are. Always rely on gross (pre-tax) income for accuracy.
Ignoring Other Debts
The rent-to-income ratio only looks at rent compared to income, but it leaves out other big expenses like student loans, credit cards, or car payments. So even if a tenant’s ratio looks safe, they might still be stretched too thin if they’re carrying heavy debt. That’s why it helps to also check their debt-to-income ratio along with the rent-to-income ratio to get a clearer picture of their real financial situation.
Setting the Bar Too High or Low
The “3x rent” rule is a solid industry guideline, but applying it too rigidly might cause you to miss out on good tenants. On the other hand, being too flexible could put you at risk of missed payments. The key is finding the right balance between keeping rent affordable for tenants and protecting your property income.
Not Adjusting for Local Markets
As mentioned, the ideal rent-to-income ratio can vary significantly by location due to differences in the cost of living and average income levels. A 30% ratio might be standard in one area, but may need to be adjusted higher (e.g., 35-40%) in expensive cities or lower in more affordable areas.
Overlooking Roommates or Combined Incomes
For shared rentals, landlords sometimes evaluate applicants individually rather than as a group. In reality, the combined gross income of all tenants provides a clearer picture of affordability and reduces the risk of payment issues.
Violating Fair Housing Law
Apply rent-to-income criteria consistently to all applicants and avoid any form of discrimination. According to the NFHA, you can ask questions to confirm eligibility, but never those that reveal protected characteristics like race, religion, or family status.
What’s Next for Rent-to-Income Ratios?
Ever wonder if the rent-to-income ratio will keep holding up as the gold standard for measuring affordability? The truth is, it’s changing, shaped by shifts in the economy, housing policies, and local market realities.
After peaking in 2022, the national RTI has started to cool down thanks to slower rent growth and rising wages. But don’t let that fool you: according to the U.S. Department of the Treasury, ratios in high-demand coastal cities are still stretched thin because of limited housing supply, while more affordable regions are seeing healthier numbers.
Add to that the impact of new regulations, and the picture gets even more complex. Some policies are meant to make housing more affordable, but others may unintentionally drive rent higher. That’s why for landlords, the RTI ratio remains a useful benchmark, but it’s not a crystal ball. Pairing it with context like debt levels, income stability, and market trends will give you a much clearer sense of tenant affordability.
Moving Forward With LeaseRunner
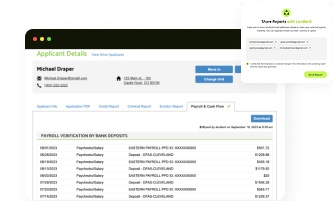
At LeaseRunner, we know how important it is for landlords to have confidence in their tenant screening process. That’s why we make it simple to go beyond the rent-to-income ratio. With our platform, you can quickly verify tenant income, run a full tenant background screening and even streamline your rent collection process.
Whether you’re managing one unit or an entire portfolio, having the right data at your fingertips helps you protect your investment and attract reliable tenants. If you’re ready to take the next step, LeaseRunner gives you the tools to screen smarter and manage with peace of mind.
Final Thoughts
The rent-to-income ratio is one of the most effective ways to evaluate rental affordability. Whether you're a landlord screening applicants or a renter setting a housing budget, understanding how the ratio works can help you make more informed decisions.
While the 30% guideline and 3× rent rule remain common benchmarks, they should be considered alongside other factors such as debt obligations, credit history, income stability, and local market conditions. Looking at the full financial picture leads to better screening decisions and more successful rental relationships.
If you're a landlord, LeaseRunner makes it easy to go beyond the rent-to-income ratio. From income verification and credit reports to background checks and online rent collection, our platform provides the tools you need to screen qualified tenants and manage your rentals with confidence.
FAQs
Q1. What percentage of income should go to rent?
Usually, rent should be limited to around thirty percent of your total monthly income. That will still leave money for food, bills, savings, and any unexpected needs.
Q2. What is a good income-to-rent ratio?
Aim for an income-to-rent ratio of at least 3:1. In practice, that means earning three times your rent each month before taxes. These criteria are used by landlords a lot to determine if someone can comfortably pay the rent.
Q3. How do I calculate my rent-to-income ratio?
First, divide your rent each month by your pre-tax income. You will then obtain the outcome by first multiplying that figure by 100.
For example, $1,200 rent ÷ $4,000 income = 0.30 → 0.30 × 100 = 30%.
Q4. How much should a tenant make to afford rent?
Use the 3× rule and multiply the rent by three. If you have to pay $2,000 for rent, for example, you should aim for around $6,000 in monthly gross income. This helps you to keep your stress down and your budget in line.
Q5. Annual Income Needed by Rent-to-Income Ratio
To estimate the annual income needed, divide the annual rent by your target rent-to-income ratio. For example, a $2,000 monthly rent at a 30% ratio requires about $80,000 in annual gross income.
Q6. How should self-employed renters prove income?
Self-employed renters typically provide recent tax returns, bank statements, 1099 forms, profit-and-loss statements, or other business income records to verify their earnings.
Q7. Does Section 8 count toward rent-to-income ratio?
It can. Many landlords consider the tenant's portion of rent and voucher assistance together when evaluating affordability. Requirements may vary based on landlord policies and applicable state or local laws.
Q8. Is debt-to-income ratio more important than rent-to-income ratio?
Neither is inherently more important. The rent-to-income ratio measures housing affordability, while the debt-to-income ratio shows overall debt burden. Reviewing both provides a more complete picture of financial stability.
Know Who Can Really Afford Your Rent
Screen tenants by verified income ratios—so you lease faster, smarter, and without late-payment surprises.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.