RS3 score vs credit score comparisons start with the same real-world contradiction: a 750-credit applicant can fall three months behind on rent, while a 610-credit tenant pays on time for two straight years. A traditional credit score answers one question: has this person repaid a loan before? It says nothing about whether this month's rent fits the applicant's paycheck.
Many property managers still reject applicants with lower credit scores and miss out on good tenants as a result. This article breaks down the RS3 score. It shows what the RS3 score vs. credit score comparison really means and why LeaseRunner built the model around rent rather than debt.
What Is a Credit Score in Rental Screening?
Before comparing the RS3 score vs. the credit score, it helps to define the older model first.
A traditional credit score, whether the FICO model or VantageScore, is a three-digit number. A credit bureau builds it from data lenders report: credit cards, auto loans, mortgages, and student loans. The formula weighs payment history, amounts owed, credit history length, new credit, and credit mix. None of those five factors considers a lease, a landlord, or a monthly rent figure.
Rental payments almost never reach a credit report at all. A tenant who pays rent on time for a decade can look, on paper, identical to someone who has never signed a lease. Applicants with a thin credit file often get no score at all, including limited history, a handful of accounts, or accounts too new to score. A landlord who leans on this score alone is using a lending tool better suited for other credit transactions.
What Is the RS3 Score (Rental Screening Science Score)?
LeaseRunner uses a different model, one designed to answer a rental question instead of a lending question. That gap is where the RS3 score vs credit score story begins.
The RS3 score, short for Rental Screening Science Score, is a three-digit number ranging from 300 to 850. It predicts the risk of rent payment default, not loan default risk. LeaseRunner designed the model in-house and runs it exclusively on its own platform. A landlord searching for what an RS3 score is can picture a familiar scale on a different engine.
Fifteen years of ACH rent collection history feed the model. Hundreds of thousands of payments feed it, too, spanning all 50 states and more than 2,000 zip codes. Default data from over 1,000 U.S. banks rounds out the picture.
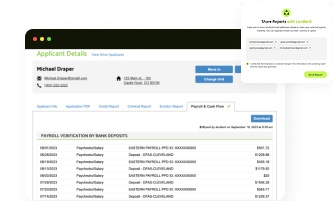
For an RS3 rental score explained simply, three inputs drive the number. Bank data tenant screening starts with verified transaction data, pulled through bank account linking. No PDFs. No screenshots that an applicant could edit. That feed includes banking metrics such as available balance, average balance, current balance, and total debits and credits. It also tracks direct deposit patterns and ACH rent payment history, where available. Cash flow analysis looks at stability over time, not at a single snapshot.
Then the score varies: it recalculates based on the exact rent for the specific unit, not a generic tier. That is the RS3 score meaning in one line. The same applicant can carry a different RS3 score at a $1,400 unit than at a $3,200 unit. Affordability changes even when the applicant does not.
How is the RS3 score calculated without touching a credit file? It is calculated from banking activity and electronic income verification instead of pay stubs. That is also why pulling it means no hard or soft credit pull. A landlord sometimes asks what a good RS3 score is. A higher number indicates a lower predicted default risk for that rent, though LeaseRunner still recommends reading it alongside the full application rather than relying on a single cutoff.
The score arrives inside LeaseRunner's screening reports and the Portable Tenant Screening Report. That is a reusable screening report that an applicant can carry over to subsequent applications for 30 days. It avoids repeat fees and supports real tenant screening without credit-check gatekeeping.
RS3 Score vs Credit Score: What's the Difference?
The plainest way to see the RS3 score vs credit score gap is side by side.
A traditional credit score and an RS3 score ask different questions, pull from different data, and land on different price tags. A landlord researching RS3 score vs FICO or RS3 vs ResidentScore is usually asking one thing. Which model predicts whether this tenant pays this rent?
FICO and VantageScore stay pure credit-bureau models. TransUnion's ResidentScore layers eviction data onto a bureau file, on its own 350–850 scale. The RS3 score skips the bureau file and builds the number from verified bank account activity instead. The table below lines up the categories that matter most.
Different questions answered
A traditional credit score predicts loan default, while an RS3 score predicts rent payment default. That difference explains most of the table above.
A mortgage lender and a landlord are not underwriting the same risk. The lender wants to know whether an applicant has repaid debt over the years. That uses a background default rate, based on national credit file performance across all borrowers, not just renters. A landlord needs something different: can this tenant cover this rent every month, starting with the first one?
The default prediction built around credit cards and auto loans does not automatically transfer to a lease. A person can manage debt responsibly and still get stretched thin by rent that eats half a paycheck. The RS3 score is trained on actual rent-payment default-rate data rather than loan default data. That is the core of the RS3 score vs credit score divide.
Different data sources
The two models pull from opposite ends of the financial system. That changes how current and complete each one really is.
A credit bureau compiles tradelines that lenders choose to furnish. Rent payments rarely make the list. Only a small share of the nation's renters carry a rental tradeline on file at all. Urban Institute reporting cites FICO's estimate of roughly 3.5% of renters as of 2024. Source: Urban Institute, 2025, citing FICO.
The CFPB's own analysis puts the figure lower, at 1.7–2.3% of renters. Source: CFPB, Tenant Background Check Markets Report, November 2022. Either way, the overwhelming majority of renters have no rental tradeline at all.
The RS3 score instead pulls bank data directly. That is why LeaseRunner is often asked whether landlords can request bank statements during screening. The honest answer: verified transaction data already replaces that manual step. Rental application data fills in the rest, covering rent amount, state, and household details a bureau file was never built to hold.
One score per person vs one score per property
A traditional credit score is portable in the wrong way. It follows the person but stays blind to the property.
The same 715 credit score can sit on file for a $1,400 unit and a $4,000 unit. Yet the second lease carries a very different rent default risk score. That is the most beneficial trait of the RS3 score. Instead of one number stamped on a person, it is a rental affordability score recalculated for the exact rent under discussion. A worked example of that gap, using real income and rent figures, follows in the affordability section below.
Coverage, credit impact, and cost
Three practical differences determine the choice between the RS3 score and the credit score for a landlord: whether a check can even run, and what it costs.
Applicants with no hard credit pull and no soft credit pull history often fall into a thin credit file category. That includes students, recent movers, and renters who simply prefer cash. A bureau model cannot score any of these applicants. International applicants with a U.S. bank account but no U.S. credit history hit the same wall. A landlord who uses bureau-only metrics when renting to applicants with weaker credit files risks turning away qualified tenants.
Screening tenants with no credit history is one of the clearest problems the RS3 score was built to solve. It reads bank activity instead of a bureau file. Tenant screening cost is the third gap. LeaseRunner prices the RS3 score well below a standard credit report. Because the check pulls bank data through an API instead of a bureau, no credit inquiry, hard or soft, ever touches the applicant's file.
Why Doesn't a Credit Score Predict Rent Payment?
On-time rent almost never reaches a credit bureau. Responsible renters get no credit for the habit that matters most to a landlord. Fannie Mae's Positive Rent Payment pilot found that when rent reporting was added, nearly 58% of participating renters saw a score increase. Renters who already had a score gained up to 40 points on average. Source: Fannie Mae, Positive Rent Payment pilot.
That blind spot creates a 500–650 gray zone. A 610 traditional credit score usually signals limited credit history, not a rental risk verdict, yet many screening policies automatically reject at that threshold. A high score is not proof of affordability either. An applicant with a 740 score who spends 52% of their monthly income on rent poses a greater real risk than an applicant with a 680 score who spends 25%, depending on the bank balances maintained.
HUD's April 2024 guidance on the Fair Housing Act makes the same point from a compliance angle. Credit scores are built to calculate the risk of defaulting on a loan, not the risk that a tenant will fail to pay rent. Rigid credit cutoffs applied to rental screening can also create disparate-impact exposure. Source: U.S. Department of Housing and Urban Development, Guidance on Application of the Fair Housing Act to the Screening of Applicants for Rental Housing, April 2024.
No published research shows that a traditional credit score alone predicts successful tenancy.
How Does RS3 Measure Affordability for a Specific Rent?
Affordability is where the RS3 score vs credit score comparison gets concrete. The RS3 score looks at the rent itself, not just the applicant.
Consider an applicant earning $6,000 a month with a $4,000 average available balance and a 715 traditional credit score. That score stays fixed at 715 whether the applicant applies for a $2,800 unit or an $8,000 unit. Yet the $8,000 rent exceeds the applicant's entire income, and the first month's payment alone exceeds the available balance on file. A landlord who runs only a credit check sees the same number on both applications and learns nothing about which lease the applicant can actually afford.LeaseRunner's income verification and cash flow report closes that gap. It pairs bank-verified income with cash flow analysis, so the RS3 score reflects the real math of that specific lease.
Overdrafts, returned checks, payroll deposit consistency, and account activity over time all feed the same cash flow-based tenant screening engine. That is why a rental affordability score built this way can flag a high-income applicant with erratic cash flow as riskier. A modest-income applicant with stable cash flow can look safer instead. A credit bureau file simply cannot make that call.
Who Benefits From RS3 Scoring?
Two groups feel the difference between the RS3 score and the credit score most directly. The benefit varies depending on which side of the lease a person sits.
For landlords
A landlord running an RS3 score gets a rent default risk score. It is built on rent payment default rate data, not a proxy borrowed from auto loans and credit cards. That is the practical payoff of the RS3 score vs. the credit score trade.
Because the score recalculates per unit, a landlord managing properties at multiple price points gets a genuinely different risk read for each one. Tenant screening cost drops, too, since LeaseRunner prices the check below standard credit report pricing. The check also surfaces qualified applicants who a bureau-only policy might have auto-rejected for a thin credit file alone. Default prediction built specifically for rent, not adapted from lending, is the core advantage a landlord is paying for.
For renters
A renter with limited credit history is not automatically screened out. A bureau that cannot generate a number does not end the conversation. An applicant with no hard credit pull on file, a recent mover, or an international applicant building U.S. financial history from a bank account rather than a credit file can still be evaluated fairly. Screening tenants with no credit history is exactly a condition the model was designed to handle.
Bank data, protected by data anonymization standards, feeds the model instead. That beats a public records search, which risks a false match due to a common name or address. The applicant's own traditional credit score also never changes during the check. Pulling an RS3 score involves no soft credit pull, a real advantage for a renter applying to several properties in the same week.
Should Landlords Use RS3 Instead of a Credit Score?
For a landlord searching for a genuine credit score alternative for landlords, purpose-built for rent instead of adapted from lending, the honest answer is straightforward.
A traditional credit score still has a place. It can flag serious debt problems, past bankruptcies, or collections a landlord may want to see. The core rental question is different: can this tenant pay this rent? The RS3 score is purpose-built for that question, where the bureau model is only a workaround. Many landlords on LeaseRunner run both a light credit reference alongside the RS3 score, rather than treating either one as a stand-alone verdict. That combination gives a landlord a fuller picture than any single number can provide.
How to Get an RS3 Score
Turning the RS3 score vs credit score debate into a real decision takes a few steps.
A landlord requests a rental application through LeaseRunner. The applicant links a bank account via a secure connection rather than uploading pay stubs or bank statement PDFs. The RS3 score and full income verification results appear inside the screening report within minutes. Both arrive alongside the Portable Tenant Screening Report. An applicant can reuse that report across other participating properties for 30 days, without paying for a fresh RS3 score each time.
Landlord flow
From the landlord's perspective, the process fits within the existing LeaseRunner application flow, with no additional steps to manage.
The landlord posts the rental listing and invites an applicant to apply. The screening report already includes the RS3 score and the affordability read for that unit's exact rent. It also includes the standard background and eviction history. The landlord never has to open a separate account, negotiate an extra fee, or review a bank statement by hand. The report already has it covered.
Tenant Flow
On the applicant's side, the process requires a bank connection rather than a stack of documents.
The applicant links a bank account once. The same reusable screening report carries forward to the next property within the 30-day window. It spares the need for repeat fees and document uploads for every new application during that period. An applicant with a thin credit file, or no credit file at all, completes the exact same flow as anyone else. The RS3 score never depends on a bureau file existing in the first place.
Conclusion
RS3 score vs credit score comes down to which question a landlord actually needs answered. A traditional credit score was built to price loan risk, and it does that job well for lenders. It was never built to tell a landlord whether a specific tenant can cover a specific rent starting this month.
The RS3 score closes that gap using bank data and verified income. Its scale adjusts with the rent amount rather than staying frozen for the applicant. A landlord who adds the RS3 score alongside a bureau check, or uses it in place of one, gets a number trained on a different outcome. The goal is a missed rent payment, not a missed loan payment.
To see how the RS3 score works for your own rental screening, visit https://rs3score.com/
FAQs
1. Is the RS3 score the same as a credit score?
No. In the RS3 score vs credit score comparison, the two are not interchangeable. A traditional credit score, such as VantageScore, measures loan repayment history through a credit bureau. The RS3 score measures rent payment default risk through bank data and rental application data, on the same familiar 300–850 scale.
2. Does an RS3 check hurt my credit score?
No. The check never touches a credit bureau file. Pulling an RS3 score involves no hard credit pull and no soft credit pull. The applicant's own credit standing does not move.
3. Can I get an RS3 score with no credit history?
Yes. An applicant with a thin credit file, no credit file, or international status can still be evaluated. The model is built for screening tenants with no credit history, using verified bank account activity instead of bureau tradelines.
4. Why does my RS3 score change between properties?
The RS3 score is a rental affordability score, not a fixed personal rating. That is why the RS3 score vs. credit score comparison never settles on a single static number. It recalculates against each property's exact rent, so the same applicant can carry a different number at a $1,500 unit than at a $3,500 unit.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.