When rent remains unpaid, the debt is often transferred to a collection agency, triggering lasting financial consequences. Few landlords or tenants know exactly what happens when unpaid rent goes to collections until they are already dealing with it. For landlords, it represents a necessary step for debt recovery, while for tenants, it can mean a sudden drop in creditworthiness and increased difficulty in securing housing.
Within today’s article, we will explain unpaid rent collection, landlord debt recovery, and how rental collection on credit reports affects tenants. We also cover steps to take, legal rules, and solutions for both sides. Scroll down for more detailed information now!
What Is an Unpaid Rent Collection?
Unpaid rent collection refers to the process landlords use to recover missed or overdue rent payments from tenants. When tenants stop paying on time, landlords must follow legal steps to protect their income and property rights. Landlords should check what rental arrears are first, since the size of the unpaid amount often decides how serious the legal action needs to be.
Most landlords begin by trying to resolve the issue directly. They may issue reminders, add late fees if outlined in the lease or allowed under state rules, or deliver a formal notice to pay or quit. For guidance on setting penalties fairly, landlords can review rent late fee guidelines before applying these charges.
If payment is still not made, the unpaid balance may be escalated. Steps often include:
- Payment tracking tools: Many landlords rely on software that sends automatic reminders and records rent activity. Using options like rent collection online creates a clear payment trail, which becomes vital in disputes.
- Formal notices: A pay-or-quit notice warns tenants that eviction proceedings could begin under state and local law if rent remains unpaid.
- Collections agencies: If the debt continues, landlords may hire a third-party collections agency. This process damages the tenant’s credit score, and the delinquency can stay on the reports for up to seven years.
Your Rights Under the FDCPA When Rent Goes to Collections
The FDCPA protects tenants once a landlord hands unpaid rent to a collector, attorney, or outside property manager. A landlord who collects rent directly does not have to follow these rules, since they apply only after the debt changes hands.
The collector has five days from first contact to send a written notice of the debt, often called a validation notice. The notice must show the amount owed, the original creditor's name, and the tenant's right to dispute it within 30 days. If the tenant disputes in writing during that window, the collector must pause all calls, letters, and credit reporting until it proves the debt is valid.
A collector can only call between 8 a.m. and 9 p.m. in the tenant's time zone, and it cannot discuss the debt with an employer, relative, or friend. Once a tenant sends a written request to stop contact, the collector must honor it, except for one final message about a specific next step, such as a lawsuit.
Unpaid rent is a civil debt, not a crime, so a collector cannot threaten arrest or jail time. It can also not misstate how much the tenant owes.
A tenant who suspects a violation can file a complaint with the Consumer Financial Protection Bureau and has 1 year from the date of the violation to sue in court. Judges can award up to $1,000 in damages plus attorney fees, even without proof of financial harm.
What Happens to Tenants’ Credit When Rent Goes to Collections?
When unpaid rent is transferred to a collection agency, tenants face immediate and severe financial consequences. This action triggers a formal negative mark on credit reports, which directly damages credit scores and creates long-term barriers to securing loans or future housing.
What Happens to the Tenant’s Credit Score?
Once debt collectors report unpaid rent, a negative mark quickly appears on a tenant's credit report. This single collection can drop a tenant’s credit score by 50 to 150 points, significantly increasing the difficulty of securing a loan for homes. In this case, tenants may need to send a debt validation letter or dispute with credit bureaus if errors occur.
Impact on Tenant’s Ability to Rent
When unpaid rent goes to collections, tenants often face rental application denial. Many landlords run strict background checks. They see unpaid rent, late payments, or records of a formal eviction process. Such marks frequently lead to rejection.
Some independent landlords also ask for higher security deposits from tenants with poor credit. For example, if a tenant has a collection account for unpaid rent, they might need to pay double the usual deposit, as noted in the security deposit criteria suggestions.
Landlords also require tenants to prove steady income. Applicants who do not meet the 3 times the rent income rule often get denied. Collections give landlords reasons to doubt financial reliability. Tenants with unpaid rent collections face higher barriers to securing new rental housing.
1. Credit Damage
Falling behind on rent often triggers a drastic credit score drop, typically slashing a tenant's score by 50 to 150 points once the collection agency reports the debt. This negative mark remains on the credit report for seven years, significantly impairing the tenant's ability to borrow money.
Consequently, tenants may face long-term financial barriers, such as rejected mortgage applications, denial of auto loans, or predatory interest rates on credit cards, even after the original balance is paid in full.
2. Debt Owed
The total amount owed typically increases once a debt is sent to collections. Agencies frequently add service fees and annual interest, often totaling 12% or more, making it much harder to resolve the balance. Additionally, tenants occupying the unit may face eviction simultaneously; this legal process generally begins after the landlord serves a past due rent notice.
3. Difficulty with Future Rentals
Even after the debt is resolved, records of unpaid rent often persist in specialized tenant screening databases, creating a long-term barrier to securing new housing. To overcome this lasting stigma and the high likelihood of rejection, tenants often face heightened scrutiny and must provide supplementary evidence of financial stability, such as a proof-of-income letter, to demonstrate they are no longer a risk.
4. Stress and Financial Impact
Beyond the stress of aggressive collection calls, tenants face severe legal consequences that can destabilize their finances. If a court judgment is issued, tenants may be subject to salary deductions (wage garnishment) or have liens placed on their personal property.
These enforcement actions add significant financial strain, making it essential for tenants to act quickly and exercise their rights under the Fair Debt Collection Practices Act (FDCPA) to validate debts before such measures are taken. A wage garnishment order or a property lien is hard to undo once a judge signs off. That is why FDCPA validation rights matter most in the days right after that first notice arrives, not once a court date is already set.
6 Steps to Send Unpaid Rent to Collections
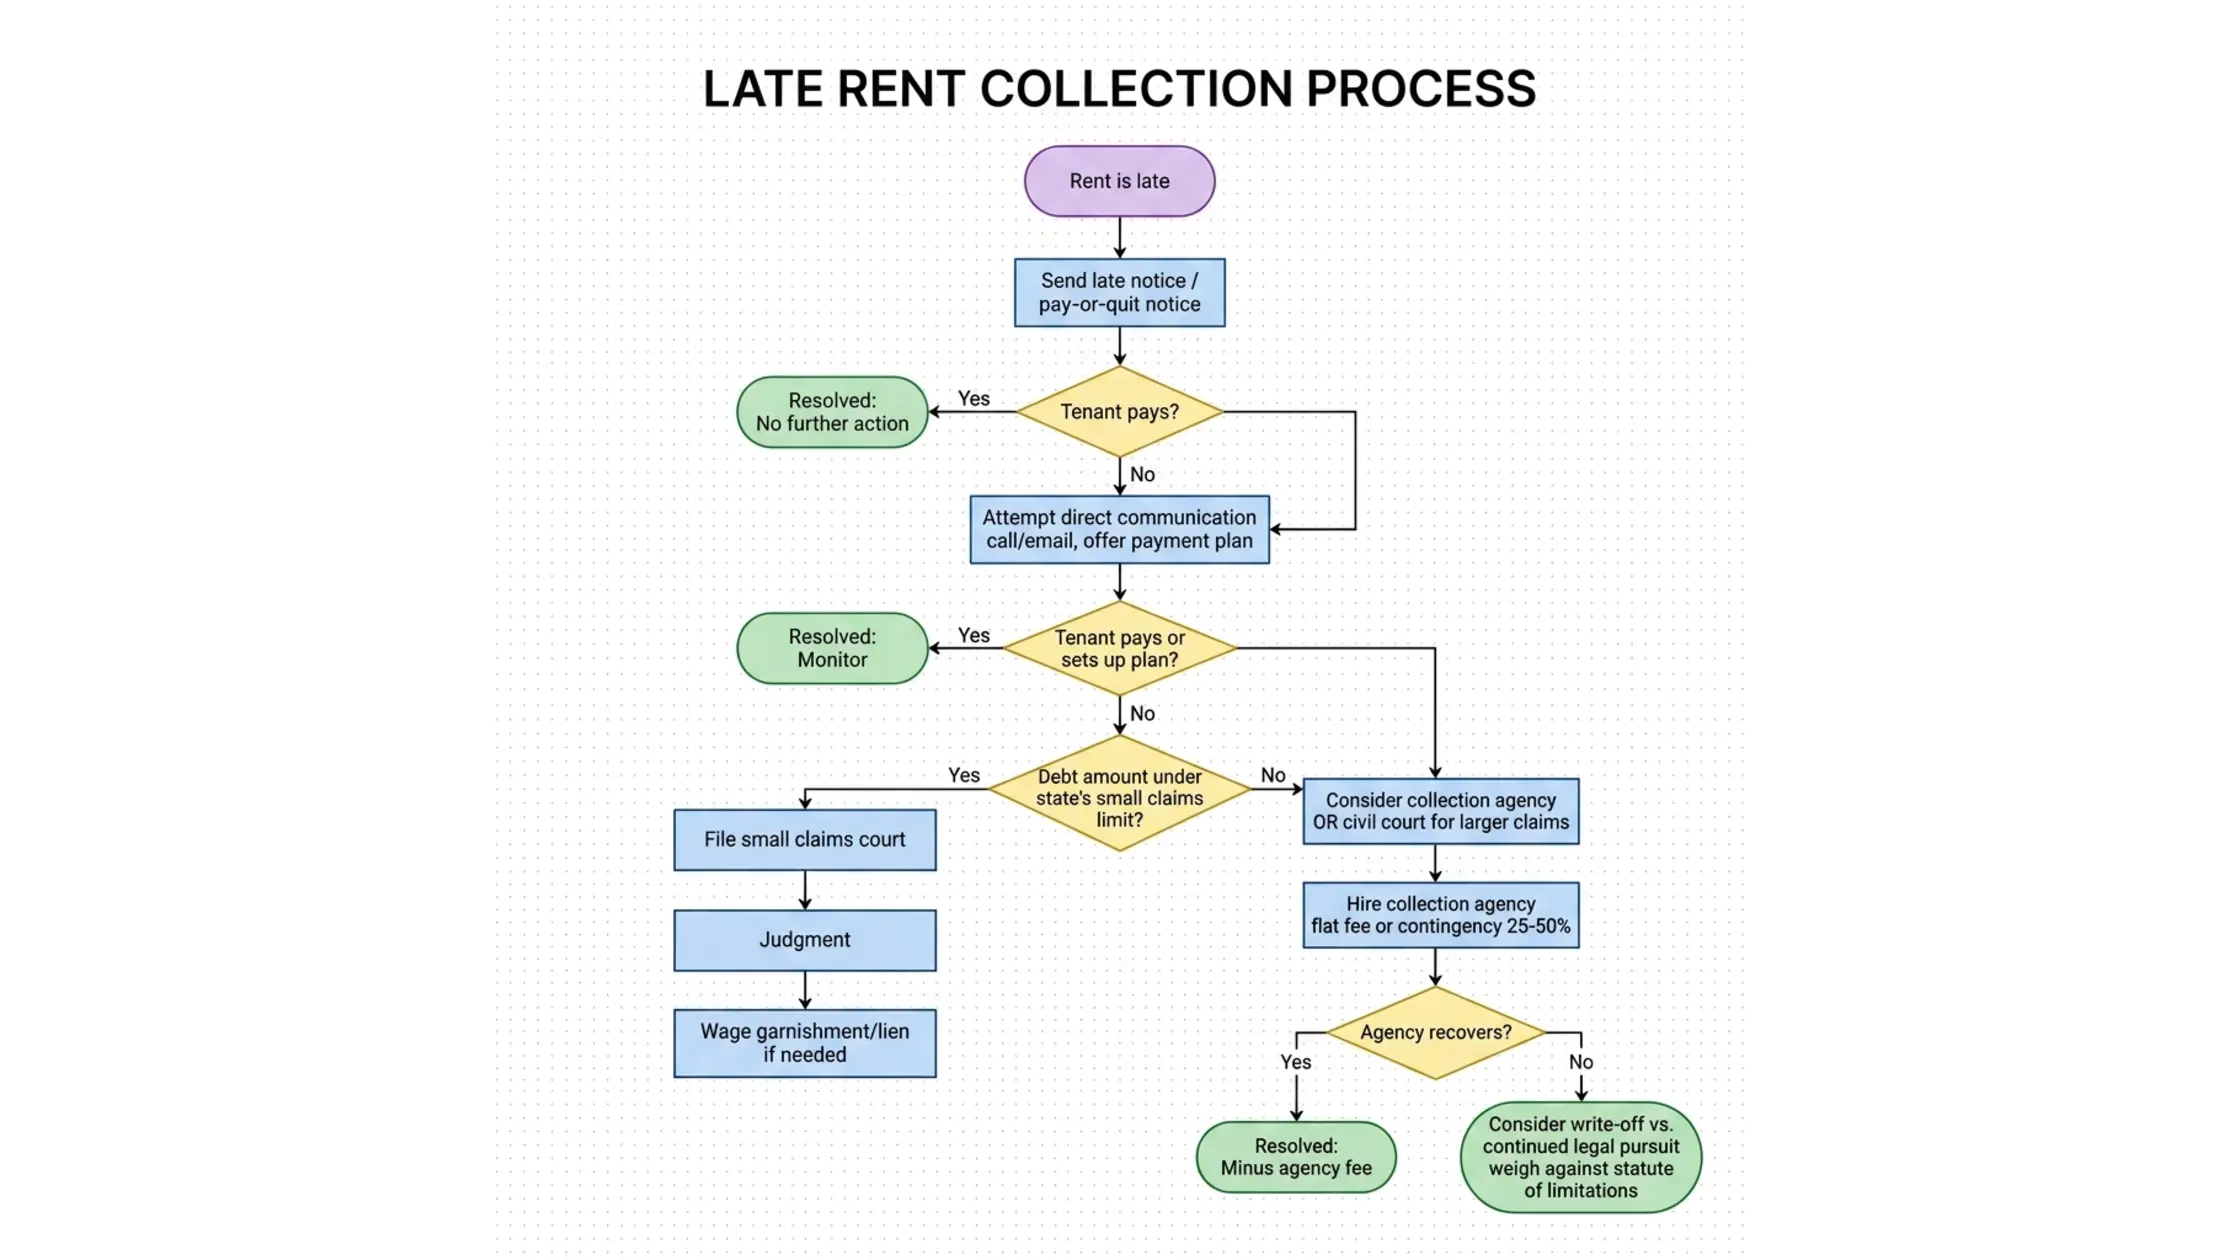
Flowchart-of-the-unpaid-rent-collection-process-from-late-notice-to-collection-agency-or-court
Tenant missed rent payments; landlords have to clearly handle overdue rent collection and debt recovery for their property. Doing this right helps landlords recover money and avoid legal trouble. Here are five simple steps landlords should follow to send unpaid rent to collections properly.
Step 1. Review the Lease and Laws
First, landlords should review state legislation and the lease. The contract must be explicit about rent due, the late charge, and what happens if rent is late or unpaid. When calculating the final claim, it is crucial to distinguish between net rent vs gross rent to ensure the debt amount is accurate.
State legislation may mandate that, before initiating tenant collections or eviction, landlords provide written notice. Knowing these rules ensures a legal procedure for collecting unpaid rent and helps landlords avoid mistakes.
Step 2. Send a Demand Letter
Landlords then formally issue the renter a demand letter. Including rent and any late penalties, this letter shows the total owed amount. It also specifies a payment deadline—typically ten to fourteen days.
The letter details what happens, including forwarding the amount to a collection agency, if the renter fails to pay. This documented attempt often matters most if the case escalates to a collection agency or court, since both typically expect proof the landlord tried to resolve the debt directly first.
Step 3: Try to Talk and Solve
Before sending the debt to collections, landlords should try to talk with the tenant. This can be by phone, email, or in person. Many tenants face money problems and may want a payment plan. For example, a tenant who lost their job might pay half the rent now and the rest later.
Talking early can often fix problems and stop the need for unpaid rent collection. It also keeps the landlord-tenant relationship better.
Step 4: Hire a Collection Agency
If the renter fails to pay or reply, landlords have the option to engage a collection agency. The agency will ask for the lease, payment records, and letters sent. The agency then attempts to collect the debt for a percentage or fee.
Good agencies enable landlords to comply with regulations like the Fair Debt Collection Practices Act. It also guards against legal danger for landlords. And this is also the answer to the question of "When can a landlord send a tenant to collections?", once the renter has failed to pay or reply to the demand letter.
Following direct attempts at communication and formal notification, the landlord can then proceed with debt recovery through a collections agency, a method that is typically employed after exhausting all direct collection attempts. This step should be taken only after the landlord has meticulously followed the prior steps to ensure compliance and avoid legal issues.
Step 5: Participate in the court session
If a tenant fails to pay and the collection agency is unsuccessful, landlords may need to take legal action to recover the money. Filing a lawsuit, typically in a small claims court, is often the next step. A landlord can pursue a money judgment for the unpaid rent and any related fees.
Here is what this process usually involves:
- Filing the Claim: The landlord files a claim with the appropriate court and serves the tenant with the court papers, which state the amount of money owed and the date of the hearing.
- Preparing for the Hearing: At the court session, a landlord must present a clear case with strong evidence. This includes providing a copy of the signed lease agreement, detailed payment records, copies of all late notices and demand letters, and any other relevant communication.
- Possible Outcomes: The judge will review the evidence from both sides. If the landlord's case is successful, the court can issue a money judgment against the tenant for the unpaid rent. This court order legally confirms that the tenant owes the debt.
In some cases, if the tenant is still in the property, the court may also issue an eviction order. While getting a judgment can be a long process, it gives landlords more powerful tools to collect the debt, such as wage garnishment or placing a lien on the tenant's property.
Step 6: Track the Process
After hiring the agency, landlords must stay updated. They should ask for regular reports on payments and progress. If tenants dispute the debt, landlords may need to provide more proof. Watching the process helps landlords stay in control and make landlord debt recovery smoother and more effective.
Following these five steps helps landlords handle unpaid rent collection clearly and legally. It improves the chances of getting the money owed while lowering conflicts and legal problems.
How to Dispute an Incorrect Rent Collection
To dispute an incorrect rent collection, send a written dispute to the collection agency and to each credit bureau reporting it. State exactly what is wrong, such as a balance already paid or a debt that does not belong to the tenant, and attach proof.
A short letter covers everything needed. It should include the tenant's name and address, plus the account number from the collection notice. State the error clearly too, and list anything enclosed, such as a receipt or a copy of the lease. Something like this works:
“I am writing to dispute the rent collection account referenced above. This debt was already paid in full on [date], as shown in the enclosed receipt. Please investigate and correct or remove this entry from my credit report, and confirm the outcome in writing.”
Send the letter by certified mail with a return receipt, to the collector and to each bureau involved, such as Experian, Equifax, or TransUnion. Keep a copy of the letter along with the mailing receipt, since that receipt is the proof of when the clock started.
Under the FCRA, the bureau has 30 days to investigate once it receives the letter, and that can stretch to 45 days if the tenant sends more documents during the window. It must report the result in writing within 5 business days after the investigation ends, and if the debt cannot be verified, it has to be corrected or deleted.
If the dispute comes back verified, there are still paths forward. A tenant can take any of the following steps:
- Ask the bureau for its method of verification, which it must answer within 15 days.
- Send the dispute straight to the collector, since furnishers carry their own duty to investigate.
- Add a short statement to the credit file, which stays on record for anyone who pulls the report later.
- File a complaint with the Consumer Financial Protection Bureau or talk to a consumer protection attorney if the error is causing real harm.
Most disputes resolve well before reaching this stage, but it helps to know the next move exists.
Can a Landlord Send Tenants to Collections Without a Judgment?
Yes, they can send a tenant's unpaid rent to a collection agency without first getting a court judgment. This is because the debt is based on the signed lease agreement, which is a legally binding contract. The landlord simply needs to prove the debt is valid with proper documentation.
A landlord must still follow certain steps and laws before and after sending a tenant to collections. Once a collection agency takes over, the tenant's Fair Debt Collection Practices Act (FDCPA) rights kick in, including the validation notice and the 30 day dispute window covered earlier in this guide.
Best Practices to Prevent Unpaid Rent and Avoid Collections
The greatest approach to prevent risky unpaid rent collection is to stop issues before they occur. Employing smarter methods allows landlords to lower risks and maintain renters who make regular payments.
These are some significant recommendations meant to assist landlords in avoiding costly landlord debt collection and unpaid rent.
Screen tenants effectively to prevent payment issues
Good tenant screening is the first step. Check credit reports, rental history, employment, and income. Avoid tenants with past apartment collections or evictions. For instance, a call for a minimum credit score and evidence of income at least three times the rent. This guarantees renters can pay their rent on schedule.
Asking applicants to provide a proof of rent payment letter from their current housing provider is a reliable way to verify consistent payment habits. Get the required information by gathering using a comprehensive rental application form. Check their eviction history properly, call previous landlords and companies to confirm all specifics.
To protect your property and neighborhood, do background checks, including credit reports and criminal histories. Reliable credit and background checks are offered by providers such as LeaseRunner, with full-fledged reports you need in the tenant screening process, plus free rental applications..
Interview applicants to learn more about their rental history and habits. Ask about past late payments or evictions. This personal touch can reveal red flags not seen on paper.
Setting clear payment expectations in lease agreements
Write clear and detailed lease agreements. Specify the rent amount, due date, late fees, and grace periods. Include what happens if rent is unpaid, such as possible landlord collections or eviction.
For example, state that rent is due on the first of each month, with a five-day grace period. After that, a late fee of $50 applies. Also, mention that unpaid rent may be sent to collections after 30 days. Specifying a clear grace period on rent within the lease agreement prevents confusion about when penalties actually kick in.
Clear lease terms prevent confusion and give landlords a strong legal basis for landlord debt recovery if needed. Tenants who understand the rules are more likely to pay on time.
Communication strategies to address late payments early
Act quickly when rent is late. Contact tenants by phone, email, or text to remind them. Ask if they are facing problems. Many tenants want to pay but need help.
Offer payment plans when needed. For example, if a tenant loses a job, agree on paying half the rent now and the rest in the next two months. This keeps the tenant in good standing and avoids unpaid rent collection.
Keep all communication in writing. Document phone calls and emails. This record helps if the debt goes to the landlord's collections or the court.
Offer Multiple Payment Options
Tenants miss rent less often when they have more than one way to pay it. A single method that does not match how someone gets paid, like requiring a check from a tenant who is paid in cash or through a gig app, can turn an on time tenant into a late one.
Most landlords now offer at least a bank transfer, a debit or credit card option, and a backup method such as a money order for tenants without a bank account or a card. A bank transfer usually carries no fee, while card payments are quicker to set up but often add a small processing fee.
Giving tenants a choice removes the most common excuse for a late payment, that the one accepted method did not work that month. A platform built for online rent collection can offer several of these methods in one place, so the landlord is not the one juggling checks, transfers, and receipts by hand.
Additional Tips to Avoid Unpaid Rent Collection
- Use online rent payment systems. These make paying easy and provide automatic reminders.
- Enforce consistent policies for all tenants to avoid discrimination claims.
- Conduct periodic property inspections to maintain contact and spot issues early.
- Educate tenants about the consequences of unpaid rent, including credit damage and collections.
- Adopting a method for collecting rent, such as automated online transfers, creates a digital paper trail that protects both parties.
State-Specific Statute of Limitations
The statute of limitations sets the deadline for taking unpaid rent to court, and it differs by state. Since a lease counts as a written contract almost everywhere, the table below uses each state's written contract deadline, compiled from Nolo's legal encyclopedia. The clock usually starts on the date of the last missed payment.
A few states, such as Colorado, set a separate and longer deadline specifically for rent rather than using their general written contract period, and that rent specific number is what's shown above. These limits can also change, and some states allow exceptions that pause or extend the clock, so it is worth confirming the current law before relying on any single number here.
Summary
What happens when unpaid rent goes to collections shapes the next several years for everyone involved. For landlords, unpaid rent collection and landlord debt recovery can help get back money, but can also bring stress and legal steps. For tenants, apartment collections and a rental collection on a credit report can hurt credit for seven years.
The best plan is to prevent problems: screen tenants, write clear leases, and talk early. LeaseRunner's effective tenant screening service offers landlords a simple, secure platform to screen tenants and collect rent online, helping reduce late or unpaid rent issues while keeping processes streamlined and transparent.
If collections are needed, know your rights and what to do, including how to dispute apartment collections and how long collections last.
FAQs
Q1. How Long Does Unpaid Rent Stay on Credit?
Unpaid rent collections stay on a tenant’s credit report for seven years. This period starts from the first missed payment. Even if the tenant pays later, the collection record remains. It may show as “paid” or “settled,” but the negative mark stays for the full seven years.
Q2. How to Dispute Apartment Collections?
Tenants can dispute apartment collections if they believe the debt is wrong. To do this, tenants should:
- Request proof of the debt from the collection agency.
- Gather payment records and any communication with the landlord.
- File a dispute with the credit bureaus (Experian, Equifax, TransUnion).
The credit bureaus must investigate and fix any errors within 30 days.
Q3. What Are the Risks of Using a Collection Agency?
Collection agencies charge fees, often 20% to 50% of the recovered amount. A few agencies could use aggressive methods. If they violate the laws, landlords take the risk of legal action. Hiring respectable companies that abide by the Fair Debt Collection Practices Act is crucial.
Q4. How Can Landlords Improve Debt Recovery?
Landlords should keep detailed records of payments and communications. Using a good collection agency helps. Following state laws and lease terms is vital. Clear documentation supports the landlord’s claim and speeds up recovery.
Q5. What Should Tenants Do If Sent to Collections?
Tenants should contact their landlord to discuss the debt. Seeking legal advice quickly can help protect their rights. Tenants should also check their credit reports and dispute any errors. Acting quickly can reduce credit damage.
Q6. Can Tenants Remove a Rental Collection from a Credit Report?
Tenants can remove a collection only if the debt is incorrect or has already been paid. They must contact the collection agency and credit bureaus to request removal. Otherwise, the record stays for seven years.
Q7. What are the typical costs for a landlord to use a collection agency?
Collection agencies typically charge a fee based on the amount they successfully recover. This fee usually ranges from 25% to 50% of the total debt collected.
Q8. Can you negotiate a collection amount or pay-for-delete agreement?
Yes, both are possible, though neither is guaranteed. A collector can agree to accept less than the full balance, and some will agree to delete the account from the credit report once paid, known as pay for delete. Credit bureaus generally discourage this practice, so get any agreement in writing before sending money.
Q9. Does the 7-year credit report rule reset if the debt is sold to a new collector?
No. The seven year clock is tied to the date of the original missed payment, not to who currently owns the debt. Selling or transferring the account to a new collector does not restart it, and a collector that tries to report a newer date is breaking federal law.
Recover Rent. Protect Your Business.
Handle late payments legally and keep your property cash flow steady.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.