An eviction can make it harder to get approved for future rentals, but some eviction records can be removed, sealed, corrected, or disputed depending on the situation and state law. Taking the right steps early may also reduce the impact on a tenant screening report, rental history, or credit report.
This guide explains how to remove evictions from record, how to check where the eviction appears, and what options may help improve approval chances for future rental applications.
What Does Eviction Record Actually Mean?
An eviction record usually refers to information connected to an eviction lawsuit, unlawful detainer case, or eviction judgment stored in court records or screening databases. Different records affect renters in different ways.
Many tenants assume every eviction appears everywhere forever. In reality, eviction information can appear in several separate systems. Some records remain only in housing court files, while others appear on a resident screening report or credit file after unpaid rent goes to collections.
1. Court Record: The Judicial Decision
A court record comes from a housing court, county court, or civil court after a landlord files an eviction lawsuit. Some states use the term unlawful detainer instead of eviction filing.
Court records may include:
- Eviction filing date
- Case number
- Eviction judgment
- Dismissal
- Settlement agreement
- Writ of possession
- Outstanding rent claims
Court filings often become the source for tenant screening companies and specialty consumer reporting agencies that collect public housing records.
2. Credit Report: The Financial Impact
An eviction itself does not usually appear directly on a credit report. However, unpaid rent or court-ordered debt may appear as a collections account.
A landlord or collection agency may report:
- Unpaid rent
- Lease-breaking fees
- Court costs
- Property damage claims
Major credit bureaus operate under Fair Credit Reporting Act (FCRA) rules requiring reasonable procedures for accuracy. A rental applicant has the right to dispute inaccurate information and request a reinvestigation.
The Consumer Financial Protection Bureau explains that eviction records usually appear indirectly through debt collection reporting rather than as standalone entries.
3. Tenant Screening Report: The Landlord’s Comprehensive Tool
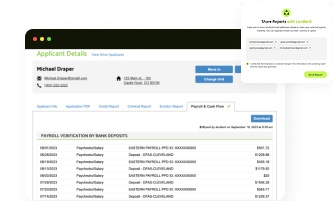
A tenant screening report gives landlords a broader view of a renter’s history, including eviction filings, unpaid rental debt, and prior lease issues. Some companies also use the term resident screening report, which generally refers to the same type of tenant screening report used during the rental application process.
Landlords and leasing offices use tenant screening reports to evaluate risk during the rental application process. A tenant screening report may contain:
- Prior eviction filings
- Dismissed cases
- Eviction judgments
- Late payment history
- Rental debt
- Negative rental history notes
Many renters first discover a screening problem after receiving an adverse action notice from a housing provider. To understand exactly what property managers see during this evaluation, applicants can review guidance on what does a rental background check show to identify hidden warning signs in their history.
Can You Remove an Eviction from Your Record?
Yes, some eviction records can be removed, sealed, corrected, or updated depending on the type of record and state law. Dismissed cases and reporting errors are generally easier to address than a formal eviction judgment.
Different eviction records require different solutions:
- Dismissed evictions: Often strong candidates for expungement or record sealing in states that allow it. Courts are more likely to seal cases when the landlord drops the lawsuit or the tenant prevails.
- Settled evictions: Some states allow sealing after the tenant completes the terms of a settlement agreement or pays the outstanding balance.
- Eviction judgments: Harder to remove because the court formally ruled in the landlord’s favor. Some states allow limited sealing or restricted public access under specific conditions.
- Errors and identity mix-ups: Always disputable. If an eviction record belongs to someone else or contains incorrect information, federal law requires the consumer reporting agency to investigate and correct inaccurate data.
A dismissed eviction can still show up on a background check, which surprises many tenants. Even though the case didn't result in a judgment, the eviction filing itself remains in court records and can be picked up by screening companies. Understanding how a dismissed eviction appears on a background check helps tenants set realistic expectations before applying for housing.
How to Remove an Eviction from Your Record Faster?
The fastest way to remove or reduce the impact of an eviction involves checking all records immediately, correcting errors, paying outstanding debt, and pursuing expungement or sealing when state law allows.
Many renters lose valuable time because they only check one report. A court database, tenant screening report, and credit file may all contain different information.
Step 1: Pull Your Records
Before taking any action, a tenant needs to know exactly what's on record. There are three places to check:
- Court records: Search the housing court or civil court database in the county where the eviction was filed. Many courts offer free online case lookup tools. Some counties charge a small fee for certified copies.
- Credit report: Under the Fair Credit Reporting Act (FCRA), consumers have the right to access free credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com. The three major credit bureaus permanently extended free weekly online access to credit reports through the site. Review each report carefully for collection accounts connected to unpaid rent, court costs, or eviction-related debt.
- Tenant screening report : The Consumer Financial Protection Bureau (CFPB) and the Federal Trade Commission (FTC) provide guidance on specialty consumer reporting agencies that compile tenant screening reports. If a landlord used a screening company during the rental application process, the landlord must provide an adverse action notice after a denial — that notice will name the screening company and explain how to check a personal tenant screening report.
Learning how to check eviction history across all three systems takes some time upfront, but it prevents wasted effort later.
Step 2: Identify the Type of Eviction
A tenant cannot remove or dispute an eviction record effectively without identifying the exact type of case first. Different eviction records follow different legal rules and require different strategies for removal, sealing, or correction.
- Dismissed Eviction: The landlord dropped the lawsuit, or the judge ruled in favor of the resident. A dismissed eviction may still appear on a background check because many screening companies collect eviction filing data from court databases before final case outcomes are updated. In some states, dismissed cases may qualify for sealing or expungement, but dismissal alone does not automatically remove the record.
- Eviction Judgment: The court ruled in the landlord's favor and issued a formal judgment — sometimes accompanied by a writ of possession. This is the hardest type to remove. Some states allow limited sealing or expungement under specific circumstances, but most states do not automatically erase valid judgments.
- Filing Without Judgment: The property manager initiated an eviction lawsuit, but the resident vacated the premises before a formal court hearing took place. Even without a judgment, the filing may still appear in court records reviewed during tenant screening.
- Inaccurate/Identity Theft Records: The record belongs to a completely different individual with a matching or similar name. Tenants frequently ask: What if an eviction report belongs to someone else? If an eviction report belongs to someone else, the issue stems from an explicit background check error that can often be removed through the consumer reporting agency dispute process once the agency confirms the error.
To understand the exact legal timelines governing these specific record variations, renters can read an in-depth breakdown detailing how long does an eviction stay on record to map out their long-term housing strategy.
Step 3: Pay Outstanding Debt
Paying outstanding rent debt may improve rental history faster, even if the court record remains visible. An unpaid collections account damages both tenant screening results and credit scores.
A landlord or collections agency may agree to:
- Mark the debt as paid
- Update rental history records
- Request removal of a collections account
- Support a motion to vacate or seal a judgment where state law allows
- Provide documentation showing the balance was resolved
Paying a collections account does not automatically remove the account from a credit report. However, a paid account is generally viewed more favorably than an unpaid collection during future screening reviews.
Some collection agencies may offer a “pay for delete" arrangement, where the agency agrees to remove the collections tradeline after payment. These agreements are voluntary, not required by law, and many agencies refuse to offer them. Any agreement should be documented in writing before payment is made.
Vacating an eviction judgment is usually a separate legal process handled through the court system. In many states, a landlord cannot simply erase a judgment without court approval, although a landlord's cooperation may help support the request.
Resolving the debt also removes a major objection during landlord negotiations (Step 6). A landlord is far more likely to cooperate with a tenant who has satisfied the outstanding balance.
Step 4: Petition for Expungement (Court Record)
Expungement or record sealing limits public access to an eviction case and may reduce the likelihood that the case appears in future tenant screening reports. However, screening companies may not update records immediately, so tenants often need to follow up directly with the reporting agency after a court grants sealing or expungement.
Not all states allow eviction expungement or sealing, but for tenants in eligible states, this can be one of the most effective ways to limit public access to an eviction record.
General process (varies by state):
- Obtain a copy of the court case file from the clerk's office.
- File a motion to expunge or petition to seal with the housing court or civil court that handled the case.
- Pay the filing fee (typically $50–$150, though some courts waive fees for low-income petitioners).
- Attend a hearing if required. In some states, the process is administrative and no hearing is needed.
- If granted, the court issues an expungement order. The tenant should keep a certified copy and follow up with screening agencies to confirm the record has been updated.
Some states allow tenants to file pro se without an attorney, but legal aid organizations can provide valuable support, especially when a landlord contests the petition or the case involves an eviction judgment.
Step 5: Dispute Errors on Credit/Screening Reports
The FCRA gives tenants the right to dispute inaccurate information on any consumer report — including tenant screening reports. If a record is wrong, outdated, or doesn't belong to the tenant at all, a formal dispute triggers a mandatory reinvestigation by the reporting agency.
How to file a dispute:
- Obtain the report with the error (see Step 1).
- Write a formal dispute letter identifying the specific inaccuracy — wrong case outcome, wrong dates, wrong name, or a case that has been expunged.
- Submit the dispute directly to the consumer reporting agency that published the report. The FCRA requires agencies to investigate within 30 days of receiving a dispute (45 days if the consumer submits additional information).
- Include supporting documentation — court dismissal orders, expungement orders, proof of payment — with the dispute letter.
- If the agency fails to correct a verified error, the tenant can file a complaint with the CFPB at consumerfinance.gov or with the FTC at ftc.gov.
A detailed walkthrough of how to dispute an eviction on a tenant screening report covers the exact language to use and which documents carry the most weight during a reinvestigation.
Step 6: Negotiate with Your Landlord
A tenant's former landlord has more power over an eviction record than many people realize — and sometimes the most efficient path to clearing an eviction from rental history goes through a direct conversation.
Landlords can:
- Contact the court to withdraw a filing (if a judgment hasn't been entered)
- Agree to not oppose an expungement petition
- Provide a written statement confirming the matter was resolved, which a tenant can share with prospective landlords
- Contact a collections agency to request removal of a reported debt
This approach works best when the tenant has already fulfilled their obligations — paid outstanding rent, left the property in good condition, or completed the terms of a settlement agreement. Whether a landlord can stop an eviction depends on the stage of proceedings, but before a judgment is entered, there's often more flexibility than tenants expect.
Which States Allow Eviction Expungement?
Many states now allow some form of eviction expungement, record sealing, or restricted reporting, but eligibility rules vary widely. Some states provide broader tenant protections than others.
Even in states without expungement statutes, tenants retain the right to dispute inaccurate records under the FCRA. A dismissed case that shows up labeled as an "eviction judgment" is an error, and disputing it is entirely appropriate regardless of state.
For a more detailed explanation of eviction reporting timelines, renters can review how long an eviction record stays on record. Eviction laws and sealing procedures change frequently and may vary by county or court, so tenants should confirm current rules with the court clerk, local legal aid organization, or a housing attorney before filing a petition.
Conclusion
Removing an eviction from a record takes time, but many renters improve rental opportunities faster by checking reports early, disputing errors, paying outstanding debt, and pursuing expungement or record sealing when state law allows. For tenants navigating an active application with an eviction on record, understanding how to rent with an eviction on your record can open doors that standard applications won't.
LeaseRunner helps landlords and tenants navigate the screening process with transparency — including tools that help applicants understand what appears in their background check before a decision is made.
FAQs
1. How long does an eviction stay on your record?
In many states, eviction court records remain accessible unless sealed or expunged. On tenant screening reports, eviction data may remain for up to seven years under FCRA reporting standards. If unpaid rent was sent to collections, the collections account may remain on a credit report for seven years from the original delinquency date.
2. Can you get an eviction expunged?
Yes, some states allow tenants to expunge or seal eviction records. Dismissed cases usually have the strongest chance of approval. States such as California, Minnesota, Nevada, Oregon, and Colorado all provide some form of sealing or expungement process.
3. Does an eviction show up on a background check?
Yes. Most tenant background checks pull information from housing court records and screening databases. An eviction filing, dismissal, or judgment may appear on a tenant screening report even if the case never reached trial. Unpaid eviction debt may also appear indirectly through collections activity on a credit report.
4. Can a landlord remove an eviction from your record?
A landlord cannot directly erase a court record, but they may help resolve the issue. A landlord can withdraw a filing, support an expungement request, correct reporting errors, or update unpaid debt records after settlement or payment.
5. What happens if you don't pay an eviction judgment?
An unpaid eviction judgment may remain on tenant screening reports for years and may also lead to collections accounts on a credit report. In some states, landlords may pursue wage garnishment or bank levies to collect unpaid judgments. Paying or settling the debt often improves future rental approval chances.
6. Can landlords deny you for an old eviction?
Yes. Some landlords deny applications based on older eviction filings, especially when unpaid debt or multiple filings appear on a tenant screening report. However, many property managers weigh recent income stability, payment history, and current credit status more heavily than an older dismissed case.
Disclaimer: The information provided in this post is intended for general informational and educational purposes only. It should not be construed as legal, accounting, or tax advice. For guidance specific to your situation, we recommend consulting with a qualified professional in the relevant field before taking any action based on the content provided.